
Key Takeaways
- A beneficiary designation is a legal contract that pays directly to the named beneficiary, overriding your will every time.
- Retirement accounts and life insurance policies are often a family's largest assets, and your will controls none of them.
- Many divorced people never update their forms, so an ex-spouse can stay on a policy or account for years by default.
- Naming a minor child directly forces the funds into a court-supervised conservatorship, exactly what Kids Protection Planning is built to prevent.
- Review every beneficiary designation at least every three to five years and immediately after any major life event.
Written by Matthew "Web" W. Raulston, Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C. For over 15 years, Web Raulston has been a trusted advisor to individuals, families, and businesses throughout Georgia and Tennessee. A member of the State Bar of Georgia and a father himself, Web focuses on estate planning, business law, and real estate, helping clients protect what matters most through Arbor Legacy's life and legacy planning model.
A parent in Hixson leaves everything to their children equally in a carefully drafted will—perhaps meaning to split assets so no one child is favored—but their 401(k) still names an ex-spouse from a marriage that ended a decade ago. The retirement account goes to the ex-spouse, and the will has no power over that asset. This happens to families across the Chattanooga area, Franklin, North Georgia, and western North Carolina every year because most people never learn that certain assets never pass through a will at all. So do beneficiary designations override a will? Yes, and this article explains which assets they control, what goes wrong when documents conflict, and how to close the gap.
Yes, Beneficiary Designations Override a Will and Here Is Why
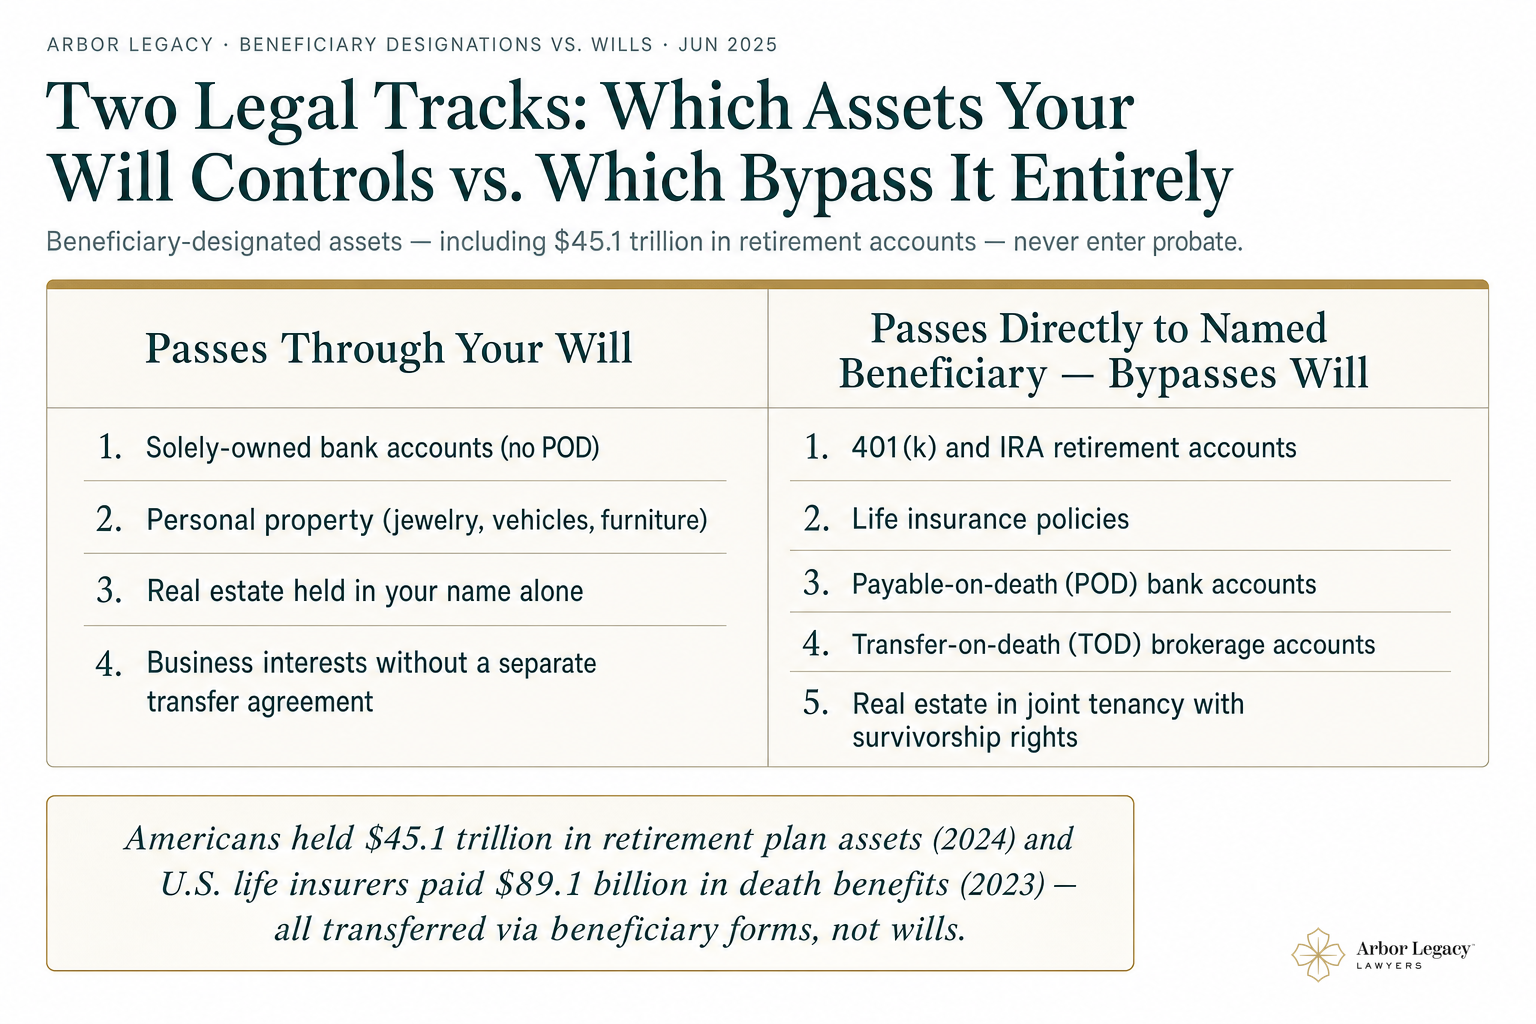
A named beneficiary on an account legally trumps whatever your will says, and the asset pays directly to that beneficiary without touching probate.
How the Contract With the Institution Rule Works
Beneficiary designations on retirement accounts and life insurance policies are contracts between the account holder and the financial institution, and in most cases financial institutions must pay the named beneficiary no matter what your will directs. In Egelhoff v. Egelhoff, the U.S. Supreme Court held that federal ERISA rules governing employer retirement and benefit plans preempt conflicting state laws, so the plan's beneficiary designation controls even when a state statute or will points elsewhere. This is why beneficiary designations can put your family at risk when left unattended.
Which Assets Are Governed by Beneficiary Designations
U.S. retirement assets outside Social Security totaled roughly $37.8 trillion at the end of 2022, according to the Congressional Research Service summary of Federal Reserve data. That number represents decades of work, sacrifice, and the security families are counting on to protect the people they love most. Most of that money passes by contract, not by will. Retirement accounts, life insurance, annuities, payable-on-death bank accounts, and transfer-on-death brokerage accounts generally bypass your will, as does real estate held in joint tenancy—a form of joint ownership—with survivorship rights. If a designation is missing or invalid, though, the asset can revert to your estate and enter probate.
Which Assets Do Pass Through Your Will
Your will controls solely owned real estate, personal property, and bank accounts without a payable-on-death feature. But for many families, the assets governed by beneficiary designations are the largest ones they own. Map your assets before assuming your will covers them, and ask the one question that actually matters about where each account would land today.
What Happens to Your Family When a Will and Beneficiary Designations Conflict
When designations are outdated, assets routinely land with ex-spouses, deceased relatives, or estranged family, creating unintended consequences that leave surviving loved ones with little recourse.
The Unintended Beneficiary Problem
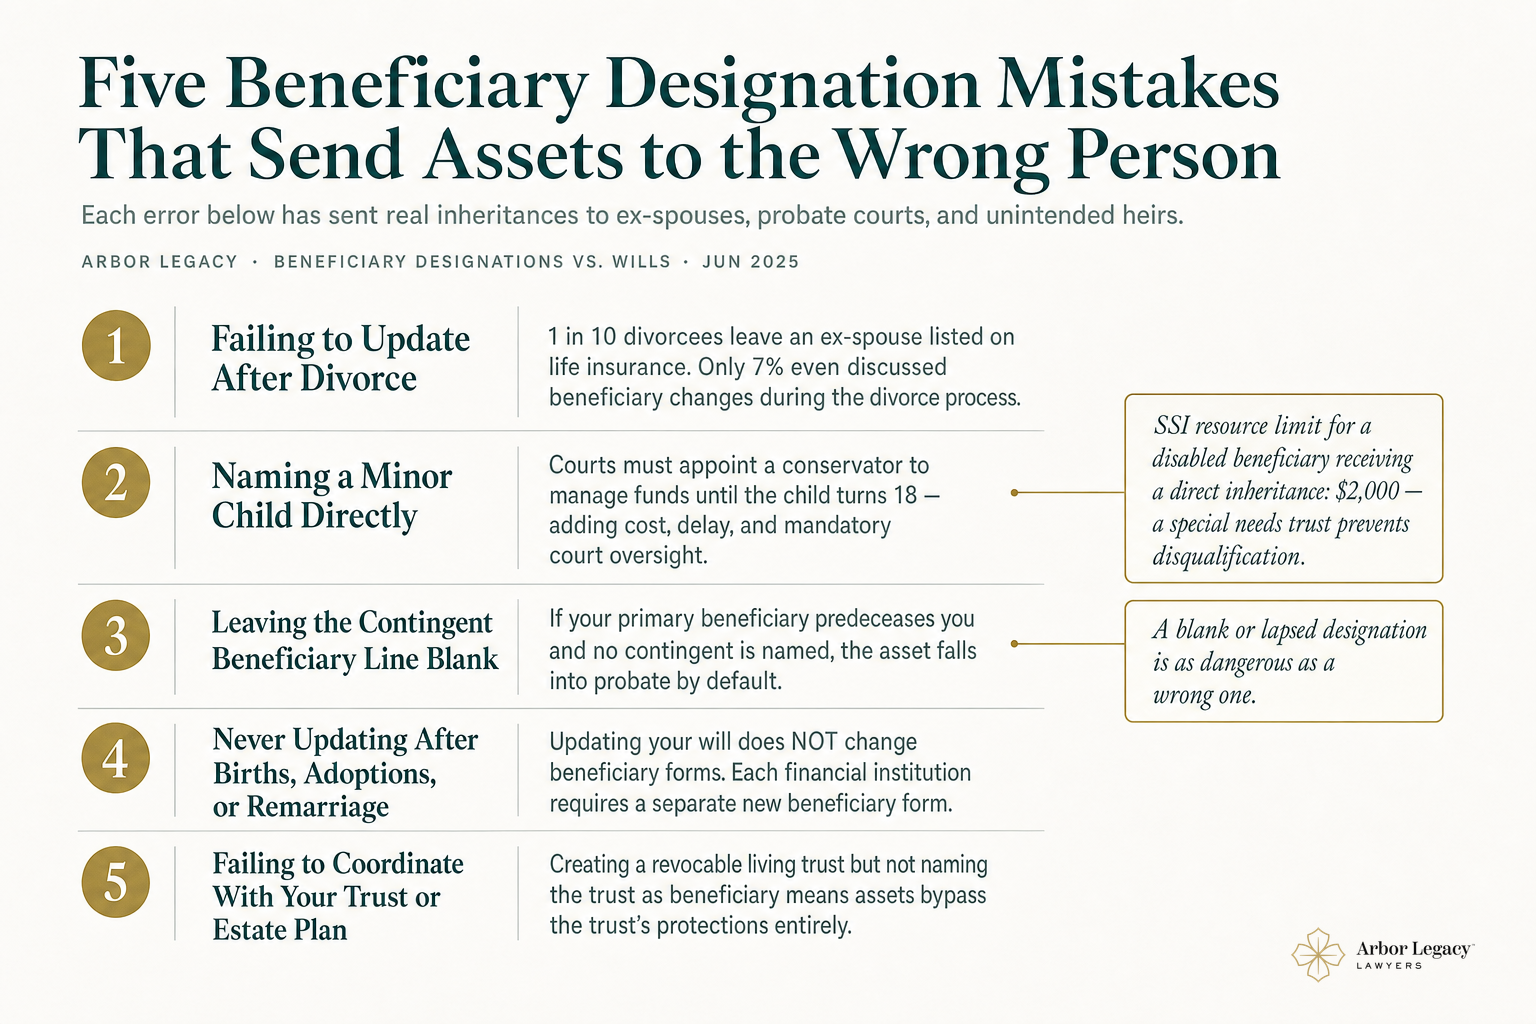
Because beneficiary changes are so often overlooked during divorce, many ex-spouses remain on policies and accounts by default for years. As of 2023, roughly 26 states have revocation-on-divorce statutes that automatically strip a former spouse of beneficiary status when the insured dies, while the remaining states leave the outdated designation in place. For employer retirement plans, ERISA preempts state revocation rules, so the last form on file controls. Divorce does not update your estate plan on its own, and neither does a completed will.
When Minor Children Are Named as Beneficiaries
A minor child generally cannot receive a large sum directly. If a minor is the named beneficiary and no trust or custodian is in place, the probate court typically appoints a conservator to manage the funds until adulthood, meaning cost, delay, court involvement, and court oversight the parents never wanted. This is exactly the scenario Kids Protection Planning is built to prevent.
When There Is No Named Beneficiary at All
A blank designation, or one where the beneficiary predeceased the account holder with no contingent named, forces the asset into probate anyway. The quick, private transfer disappears and a lengthy probate process begins. A lapsed designation can pull your family into the court system and into conflicts you never intended—it is as dangerous as a wrong one.
The Most Common Beneficiary Designation Mistakes Families Make
The key takeaways here are clear: nearly every one of these common estate planning mistakes is easy to spot once you know what to look for.
Failing to Update Designations After Major Life Events
Divorce, remarriage, a new child, and the death of a beneficiary are major life events and life changes that should all trigger an immediate review of every beneficiary form on file. IRA experts consistently point to divorce as the change most often missed. Updating your will does not update a beneficiary form, and this gap is one of the most costly beneficiary mistakes families make.
Ignoring Contingent Beneficiaries
Most people name a primary beneficiary and skip the contingent line. A contingent beneficiary is the backup who receives the asset if the primary has already died. Without one, the asset falls into your estate and goes through probate. Every account should carry both a primary and at least one contingent beneficiary. If you carry life insurance, review these common mistakes made on life insurance beneficiary designations.
Letting Designations and the Overall Estate Plan Drift Apart
The costliest mistake is treating beneficiary designations and the overall estate plan as separate systems. When a revocable living trust anchors your plan, your retirement accounts and life insurance should be coordinated with it. Because the SECURE Act imposed a 10-year payout rule on most inherited retirement accounts, naming a trust incorrectly can trigger a serious tax bill.
How Wills Still Matter Even When Beneficiary Designations Control the Largest Assets
Beneficiary forms cannot do everything, and dropping your will would leave your family exposed in ways money cannot fix.
What Your Will Governs That Designations Cannot
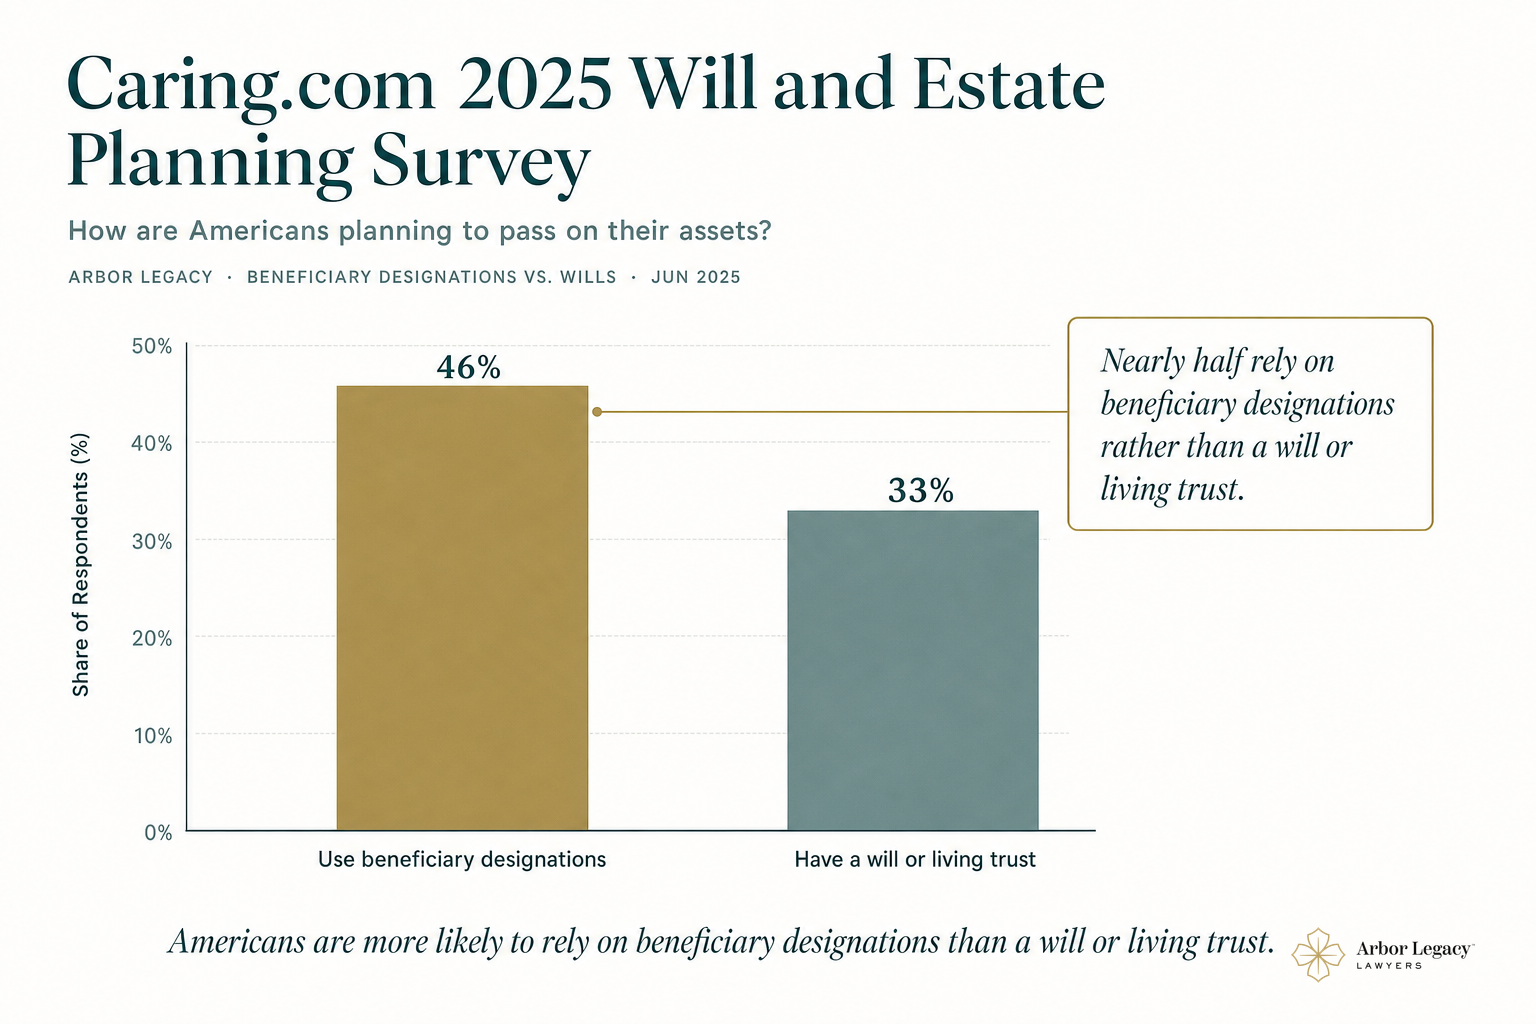
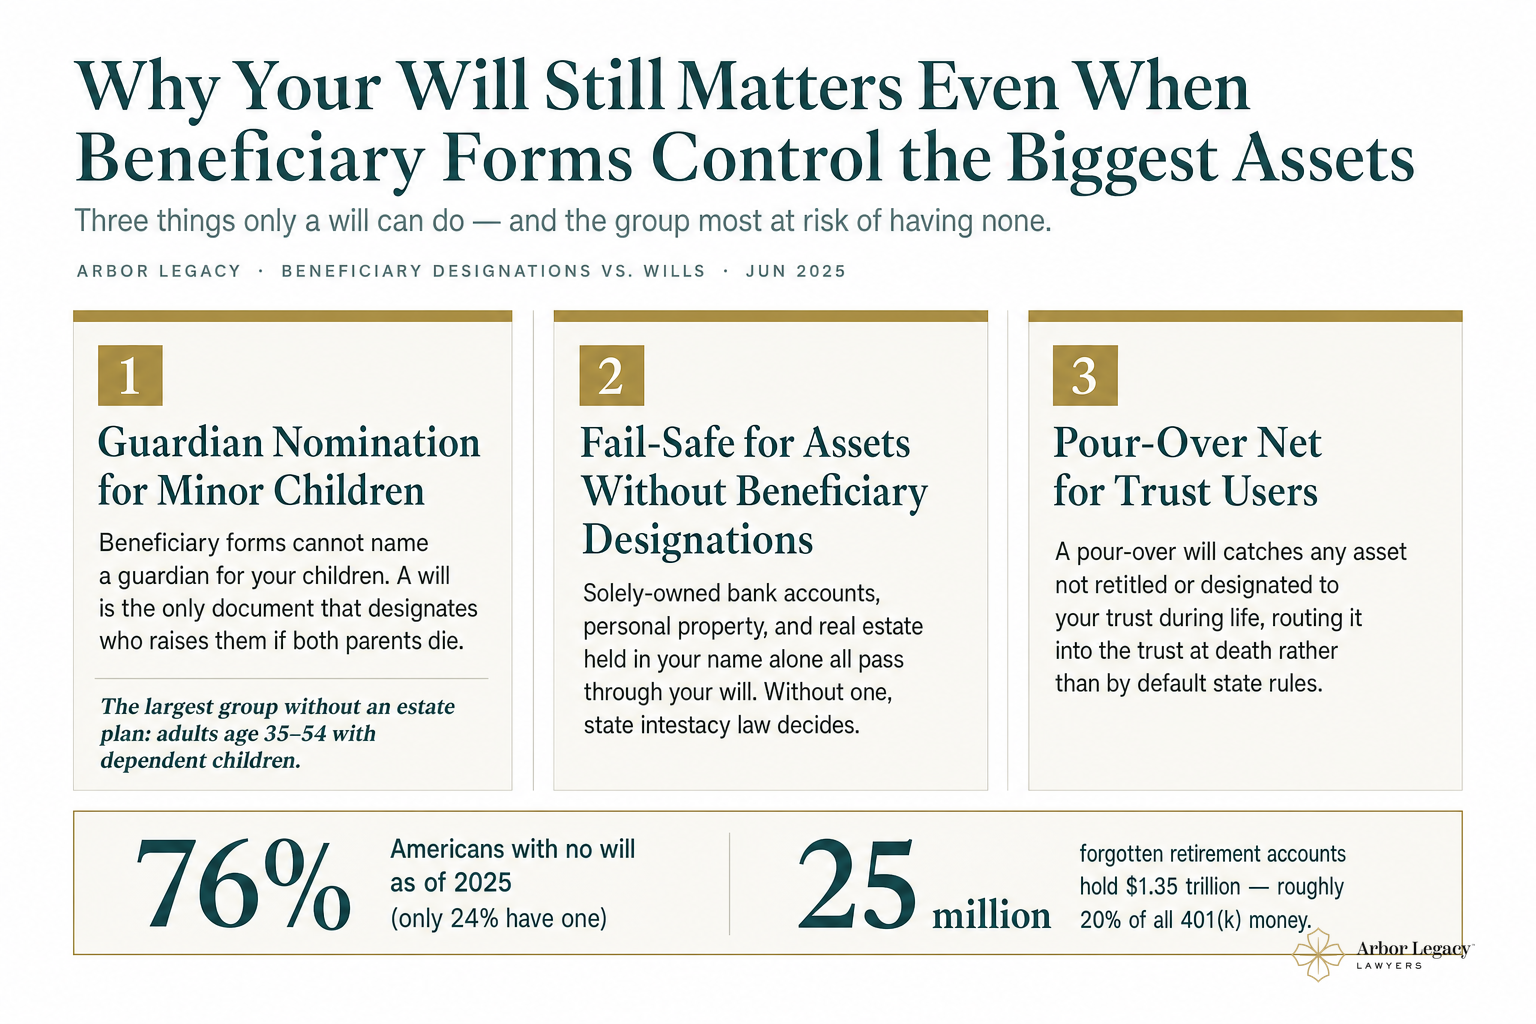
A will names a guardian for minor children. No beneficiary form can. It also directs personal property, solely owned real estate, and vehicles. Caring.com's Wills and Estate Planning Study shows that many middle-aged adults, including parents with dependent children, still lack basic estate documents, and 43% of those without a will simply say they have not gotten around to it. Those are exactly the people who most need a will for guardianship. To understand how wills and trusts fit together, it helps to see each document's distinct job.
How a Pour-Over Will Catches What Falls Through the Gaps
A pour-over will works alongside a revocable living trust. Any asset not moved into the trust during life, and lacking its own beneficiary designation, is poured into the trust at death, a safety net that keeps overlooked assets from passing intestate.
Why Your Will Is Still the Backbone of a Coordinated Estate Plan
Your entire estate plan is a coordinated system, not a stack of separate documents. Your will, trust, healthcare directives, powers of attorney, and beneficiary designations must all point the same direction. When they align, your loved ones stay out of court and out of conflict, avoiding costly legal battles and legal disputes that can tear families apart. The real test is whether your estate plan will work when your family needs it.
When to Name a Trust Instead of a Person as Your Beneficiary
Some situations call for naming a trust rather than an individual, especially where a beneficiary needs protection or guardrails.
Situations Where Naming a Trust Makes Sense
Families with minor children, a beneficiary with special needs, a loved one who needs long term care, or a loved one who struggles with money are strong candidates for a trust as designated beneficiary. Aging parents or a family member facing incapacity are also situations where elder law planning can help ensure the right protections are in place before a crisis arrives. Supplemental Security Income caps countable resources at just $2,000 for an individual and $3,000 for a couple, according to the Social Security Administration, so a direct payout can wipe out benefits overnight. A properly drafted special needs trust holds assets for a disabled beneficiary without counting against those limits.
The SECURE Act and Retirement Account Beneficiary Rules
The SECURE Act changed the rules for inherited retirement accounts. According to Grant Thornton, most non-spouse beneficiaries must now empty an inherited account within 10 years. Naming a trust requires it to be set up in a specific way the IRS recognizes—sometimes called a see-through or conduit trust—so that the account's tax advantages are preserved and unintended outcomes are avoided. Get guidance from an estate planning attorney or financial advisor before naming a trust on a retirement account, because the tax implications of even a minor drafting issue can create significant and avoidable tax consequences for your family.
Reviewing Your Beneficiary Designations Is Not a One-Time Task
The biggest risk in legacy planning is not a bad document. It is a good one no one ever revisits.
How Often You Should Review Every Designation
It is a good idea to review all beneficiary designations every three to five years and immediately after any major life event. Many people rarely do. Caring.com found only 10% of people updated their plan after a medical diagnosis and just 7% before a serious medical procedure. Set a recurring calendar reminder.
Building a Complete Asset Inventory
You cannot review what you cannot find. A complete asset inventory lists every account, policy, financial institution, joint owner, and current named beneficiary. A 2021 Capitalize white paper estimated Americans hold nearly $1.35 trillion in forgotten 401(k) accounts, so include real estate held jointly or with survivorship language too. Digital accounts belong on the list as well, since passwords alone are not enough. Keep the inventory where your family can find it.
Frequently Asked Questions: Do Beneficiary Designations Override a Will and Other Common Concerns
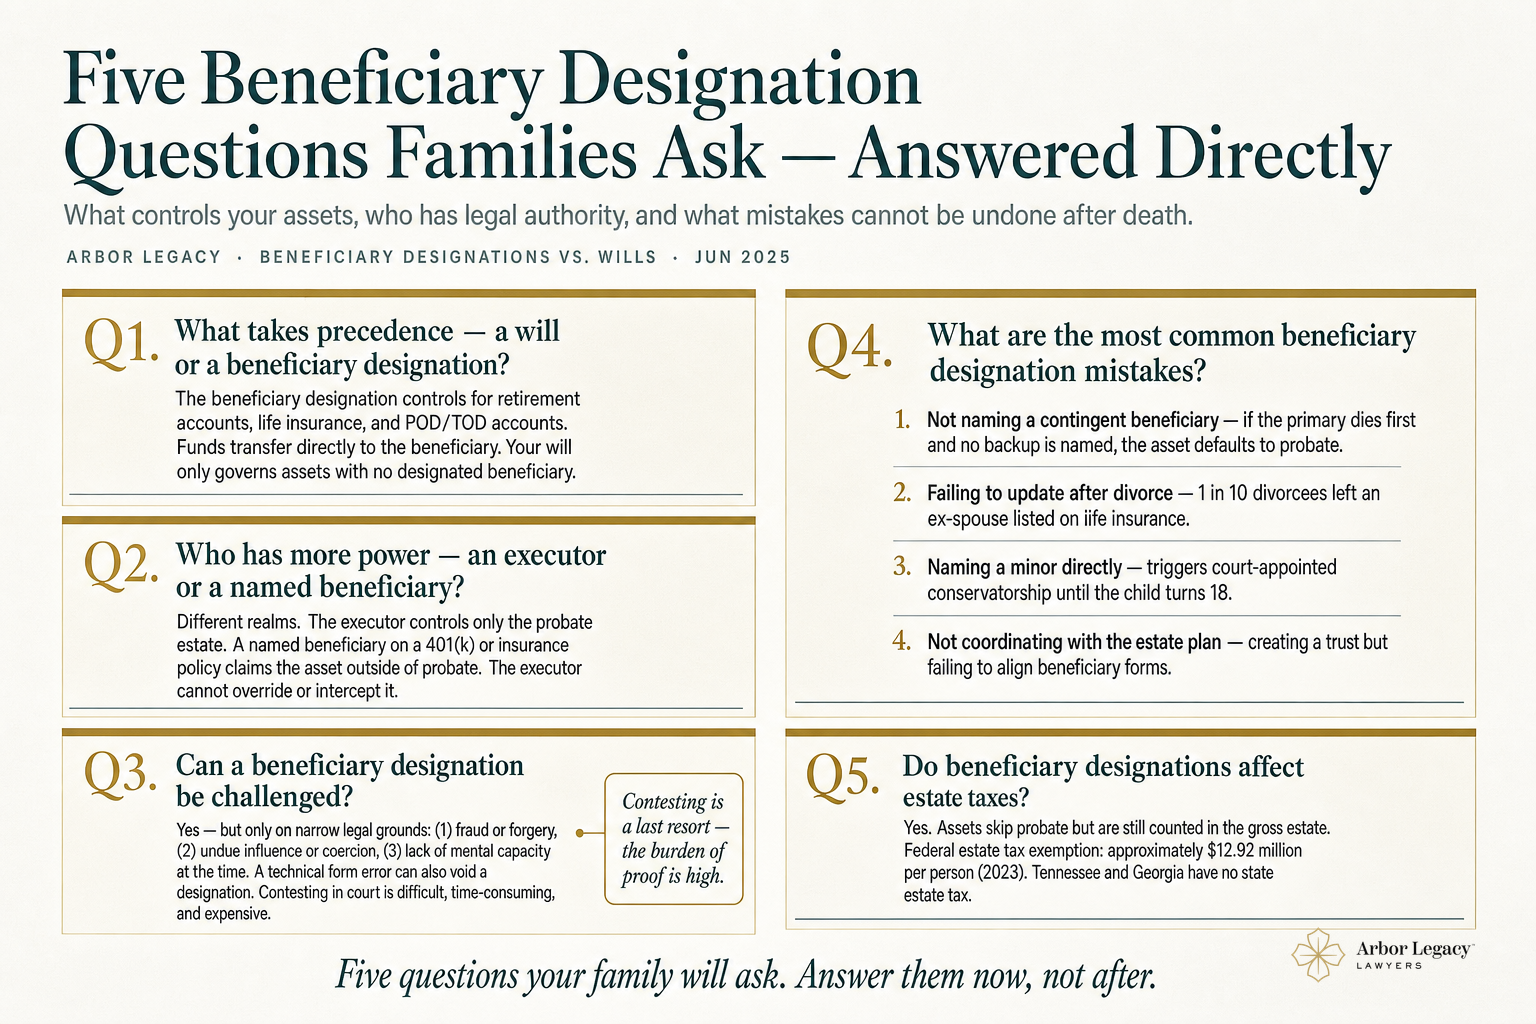
What takes precedence, a will or a beneficiary?
A beneficiary designation takes precedence for any asset that carries one. Your will controls only assets without a built-in transfer mechanism.
Who has more power, an executor or a beneficiary?
An executor controls only the probate estate, while a named beneficiary claims that account outside probate, and the executor cannot redirect those funds.
Can a beneficiary designation be challenged?
Yes, but only on valid legal grounds such as fraud, undue influence, lack of capacity, or a technical error. Contesting one in court is difficult, slow, and expensive.
What are the most common beneficiary designation mistakes?
Leaving the designation blank, skipping the contingent beneficiary, keeping an outdated form after divorce, naming a minor directly without a trust, and failing to coordinate designations with the overall estate plan are among the most common estate planning mistakes families make.
Do beneficiary designations affect estate taxes?
Beneficiary designations do not remove an asset from your taxable estate. The federal estate tax exemption was $12.92 million per person for 2023 and rose to about $13.61 million for 2024, so only a small fraction of very large estates owe federal estate tax, though current levels are scheduled to drop after 2025. A spouse named as beneficiary qualifies for the unlimited marital deduction. Neither Tennessee nor Georgia currently imposes a state estate tax. Even so, coordinated beneficiary-designation planning matters for every family—not just those with taxable estates. Getting designations right protects the people you love regardless of the size of your estate, and this level of guidance should be accessible to everyone.
What Your Family Needs You to Do Before Something Happens
The greatest threat to your family future—the values you hold, the relationships you've built, and the story you want your family to carry forward—is a good will that quietly conflicts with outdated beneficiary designations no one ever reviewed. Beneficiary designations are legally binding contracts that override your will every time. The families who avoid court disputes are the ones whose plans are coordinated, reviewed regularly, and updated after every major life change to reflect their current wishes. If a marriage has ended recently, know that divorce alone does not fix your estate plan or your spousal retirement rights.
Arbor Legacy Lawyers P.C. offers a free consultation and Life & Legacy Planning sessions across Chattanooga and Franklin, Tennessee, and in Alpharetta, Trenton, and Blue Ridge, Georgia, and serving families in western North Carolina. Schedule a Life & Legacy Planning session to build a coordinated, living plan that evolves with your family—one that keeps your designations, documents, and wishes aligned through every season of life.
This article is a service of Arbor Legacy Lawyers P.C. and is provided for educational and informational purposes only. It does not constitute legal advice and does not create an attorney-client relationship. Estate planning laws vary by state; consult a qualified attorney about your specific situation.
Matthew "Web" W. Raulston
Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C.
Arbor Legacy Lawyers, P.C.