
Key Takeaways
- A trust document only controls what you legally transfer into it. “Funding” is the step that makes the plan real, and most families skip it.
- Federal law lets you move a mortgaged home into a revocable living trust without triggering the due-on-sale clause.
- Retirement accounts should never be retitled into a trust. Update the beneficiary designation instead.
- Name a successor trustee and at least one backup so a trusted person, not a court, takes over immediately.
- Review your trust after every major life event and at least every three years.
Get insights like this in your inbox
*Written by Matthew "Web" W. Raulston, Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C.* For over 15 years, Web Raulston has been a trusted advisor to individuals, families, and businesses throughout Georgia and Tennessee. A member of the State Bar of Georgia and a father himself, Web focuses on estate planning, business law, and real estate, helping clients protect what matters most through Arbor Legacy's life and legacy planning model.
A well-drafted trust that sits empty in a Hixson desk drawer protects no one. Industry estimates suggest as many as 8 in 10 living trusts are never actually funded Enduring Legacy Mentors, which means the assets those families thought they had protected still land in probate. Nationally, probate often consumes 3 to 8 percent of an estate's value and takes 9 to 24 months Catalina Structured Funding. In Tennessee an uncontested estate commonly runs about 4 to 6 months and costs roughly $2,000 to $7,500 Batson Nolan. This guide walks you through exactly how to put your assets in a trust, asset by asset, so your loved ones stay out of court and out of conflict.
Why Funding a Trust Is the Step Most Families Miss
A revocable living trust only controls what has been legally transferred into it. Think of the trust as a bucket and funding as putting something in it. Leave the bucket empty and probate is still waiting for your family. Many attorneys do not systematically help clients fund their trusts, and clients often find the process more complicated than expected Enduring Legacy Mentors. Caring.com's 2025 survey found only 24 percent of respondents have a will and just 13 percent have a living trust Caring.com.
What "Funding" Actually Means in Plain English
Funding means retitling or re-designating assets so the trust becomes the legal owner or named beneficiary. It is a legal re-titling step, not a separate purchase. Your estate planning attorney helps you match each asset to the right method.
The Probate Trap No Document Can Fix
An unfunded trust does nothing to stop the probate process. If your home is still titled in your name at death, it goes through court anyway, defeating the entire purpose. Confirm every significant asset is titled in the trust's name before you file the trust documents away.
Revocable vs. Irrevocable Trusts
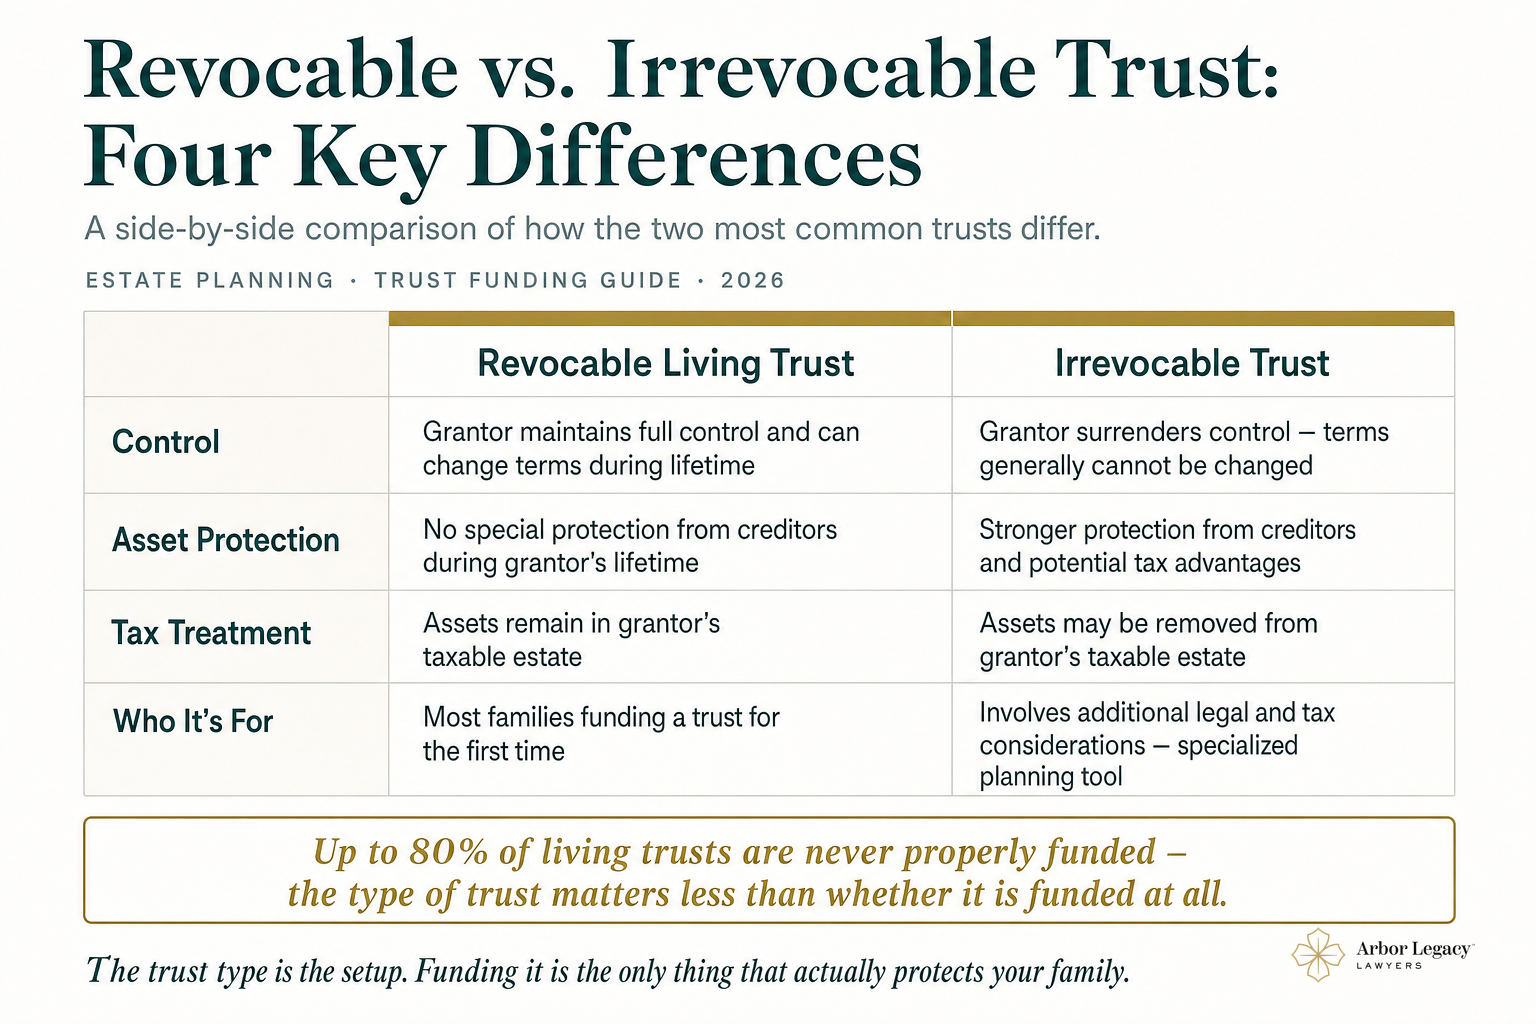
A revocable living trust lets you keep control and change terms during your lifetime. An irrevocable trust trades that control for stronger asset protection and potential tax advantages. This article focuses on the revocable trust because it is the starting point for most families.
How to Put Real Estate Into a Trust Even With a Mortgage
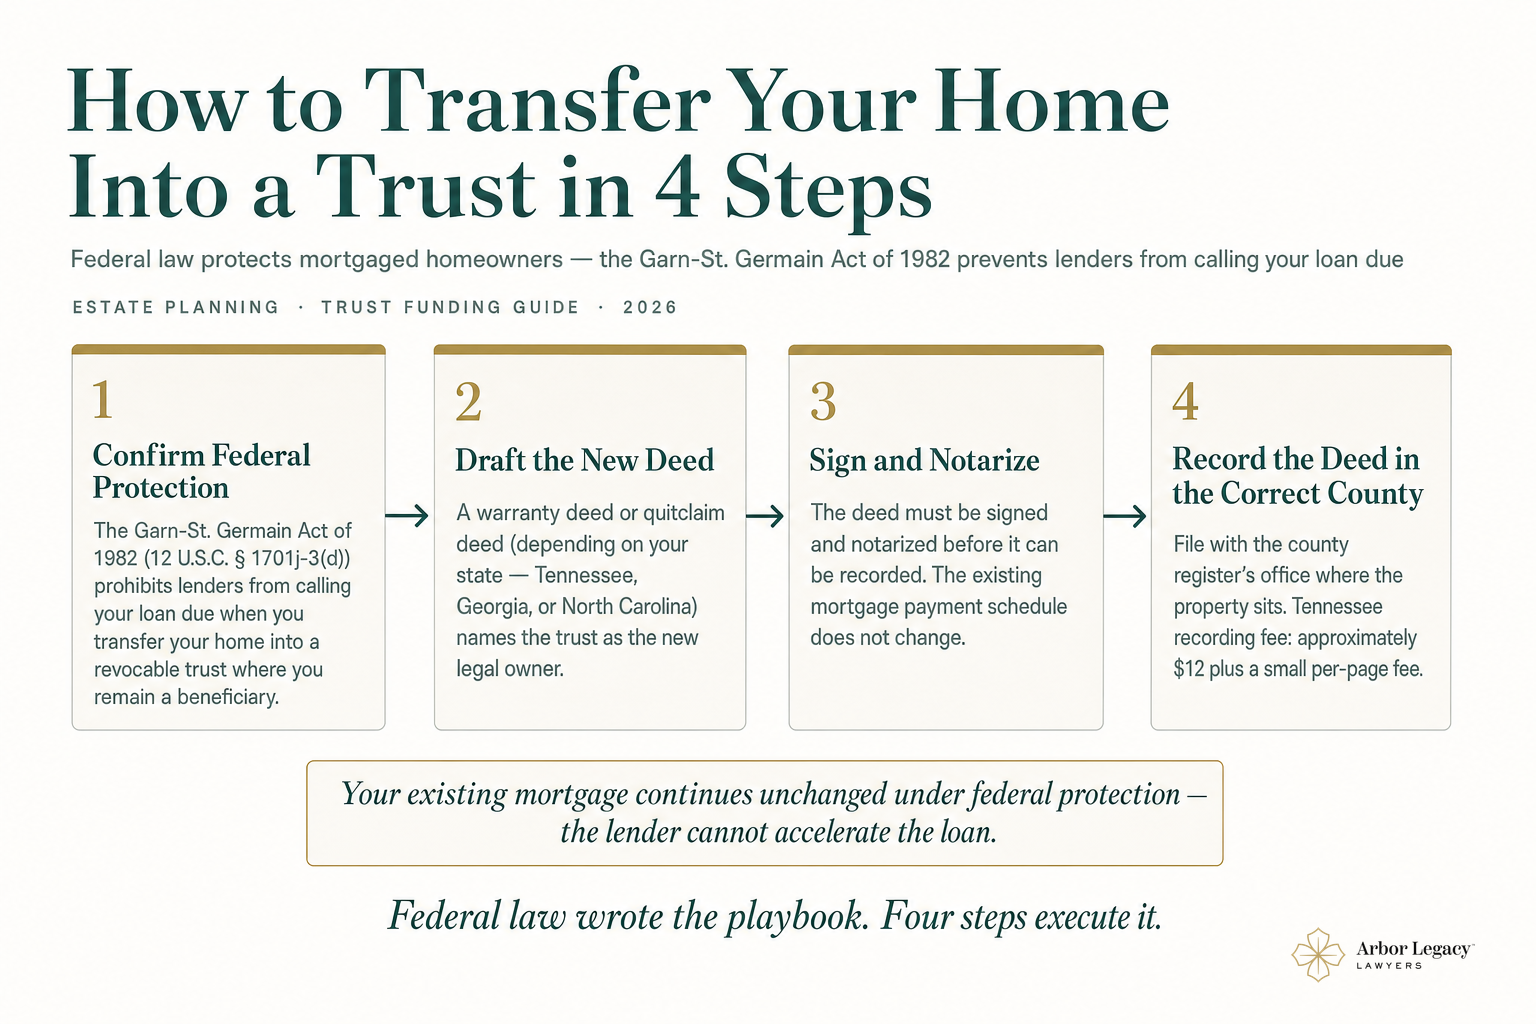
Yes, you can move a mortgaged home into a revocable living trust without triggering the due-on-sale clause, sometimes called the due clause, in most mortgage agreements. Federal law specifically protects this, so the fear that keeps many homeowners from acting is largely unfounded. Putting your family home in a trust is one of the smartest moves you can make.
The Garn St. Germain Act Protects You
The Garn St. Germain Depository Institutions Act of 1982 prevents lenders from calling a mortgage due on mortgaged property solely because you deed your primary residence into a revocable living trust where you remain a beneficiary and continue to occupy the property Cornell Law. The protection is limited to the transfer itself, a lender can still accelerate for payment default. Confirm with your lender in writing before you transfer, and review state law requirements for recording the deed in your county.
How a New Deed Transfers Your Home
A new deed naming the trust as owner is drafted, signed, notarized, and recorded in the county where the property sits, becoming part of the public record. Recording fees vary by county. Your existing mortgage and payment schedule stay exactly the same. Recording the new deed in the correct county is the legally operative step.
What Happens to Your Insurance and Taxes
Moving real estate into a trust usually does not affect your homeowner's insurance or property tax exemptions, but confirm both. Notify your insurance company so the trust is added as an additional insured, and check with your county assessor. In Georgia, homeowners can often maintain a homestead exemption when their residence is held in a revocable trust, but counties typically require a trust affidavit and verification of ownership and residency Georgia.gov.
Which Financial Accounts Should Go Into Your Trust
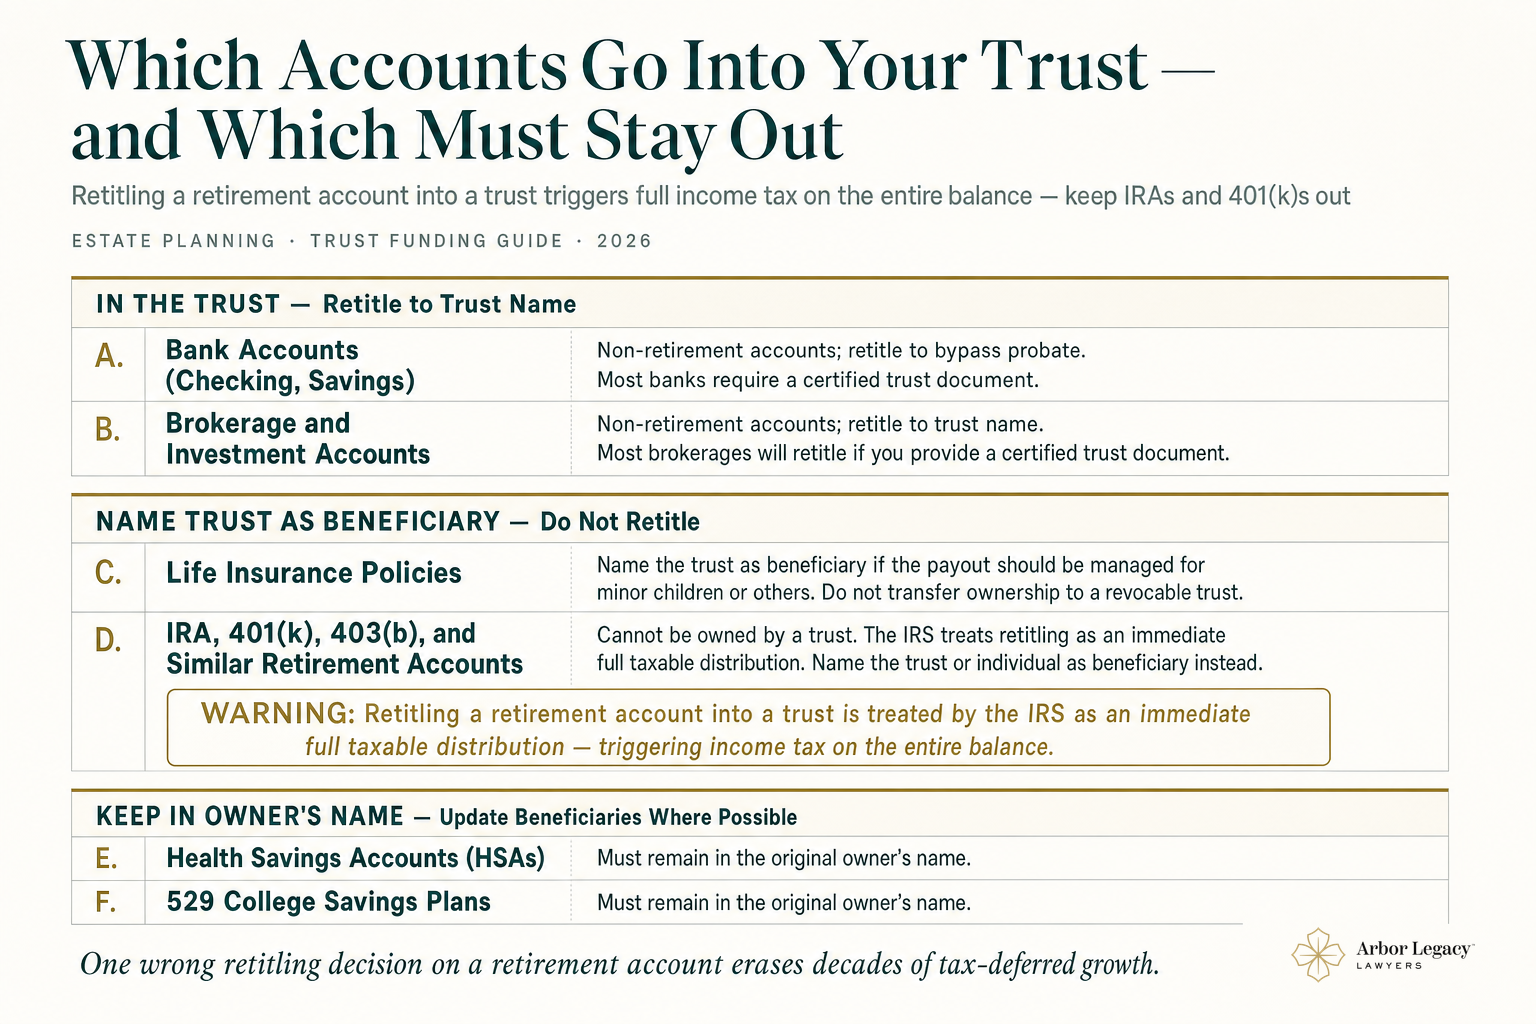
Bank accounts, brokerage accounts, and non-retirement investment accounts can and typically should be retitled into your trust. Retirement accounts are the critical exception that trips up many families.
Retitling Bank and Brokerage Accounts
Contact the financial institution, provide a certificate of trust (a short legal document the bank accepts instead of the full trust agreement), and request the account be retitled in the trust's name. Some institutions open a new trust account instead. Confirming these details protects against money later becoming unclaimed property.
Why Retirement Accounts Stay Outside the Trust
IRAs and most employer-sponsored plans must be owned by an individual; trust ownership of these accounts is not permitted. The IRS treats an IRA as something owned by one person only — move it into your trust during your lifetime and you'll owe income tax on the whole balance right away Legal Clarity. Name the trust or specific individuals as beneficiary instead. If a beneficiary has special needs, naming a special needs trust requires careful drafting to preserve government benefits.
Life Insurance Policies and Beneficiary Designations
Life insurance passes by beneficiary designation outside of probate, so a revocable trust is usually named as the beneficiary rather than the owner. That makes sense when you have minor children, a beneficiary with special needs, or an heir who should not receive a lump sum. Review every beneficiary designation to confirm it aligns with your estate plan.
Personal Property and Assets Without a Title Document
Jewelry, furniture, art, and collectibles have no deed or account number, yet they still belong in your trust. These transfer through a different, simpler mechanism.
The Assignment of Personal Property
A general assignment of personal property, sometimes called a bill of sale to trust, sweeps untitled belongings into the trust in one step. Ask your estate planning attorney to draft this as part of the trust package.
What Belongs on Your Asset Inventory
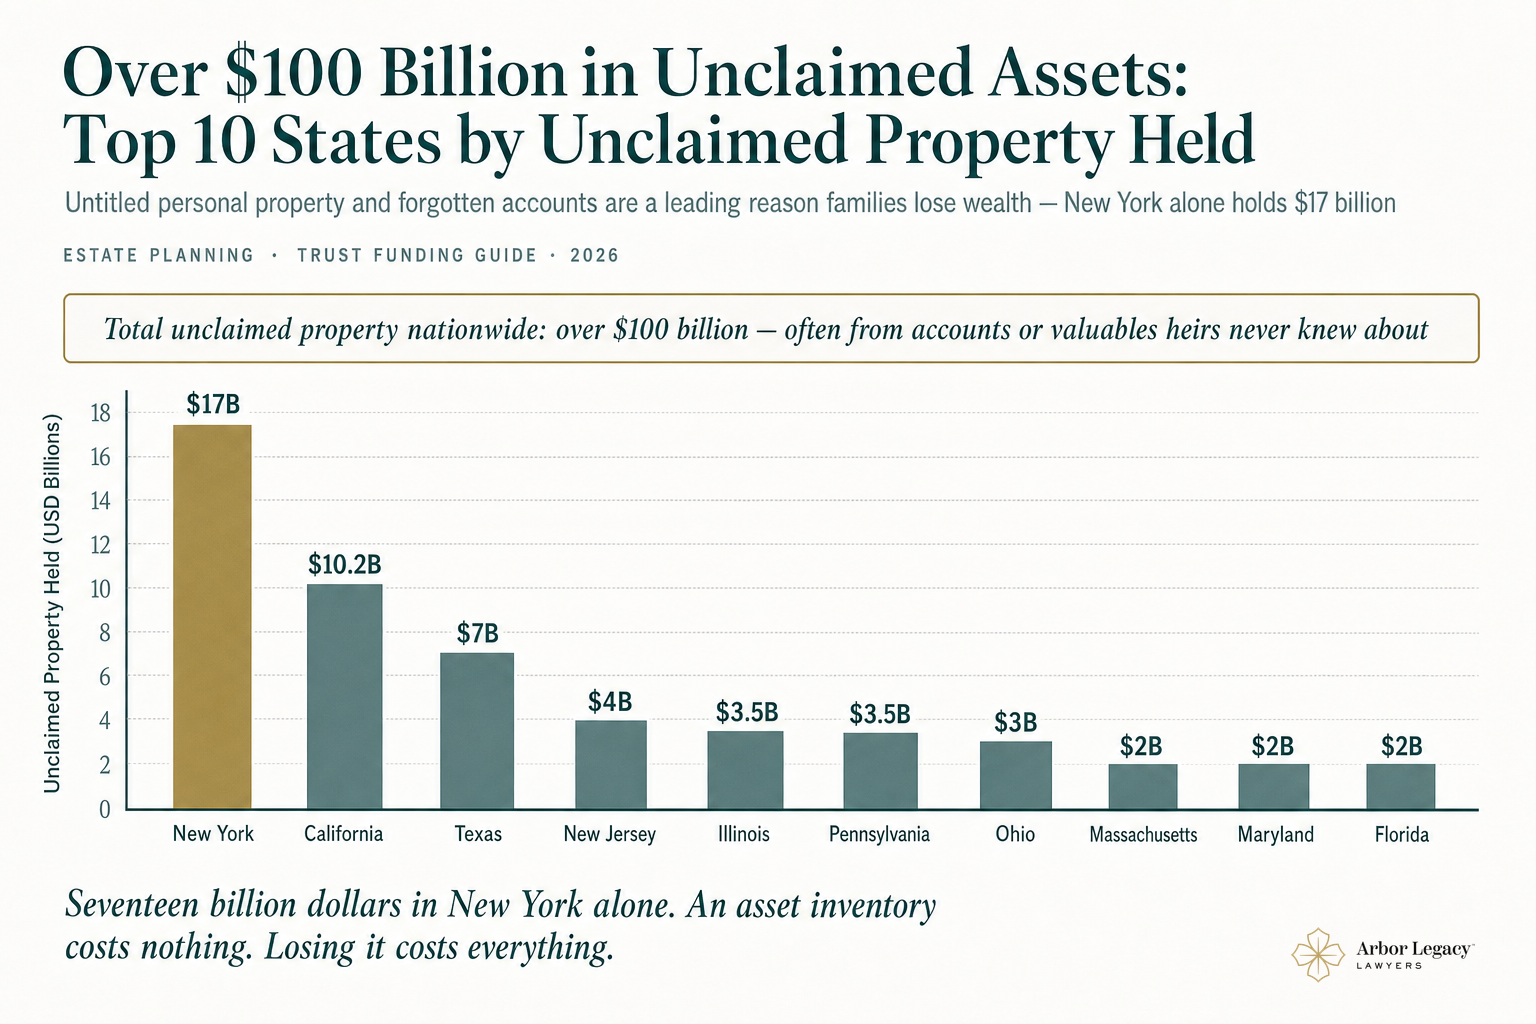
A written asset inventory is not legally required, but it keeps assets from slipping through the cracks. List descriptions, approximate values, document locations, and account numbers. State unclaimed property programs currently hold over $34 billion, with New York, California, and Texas among the largest Sparrow. Don't forget your online accounts, since digital assets belong on the inventory too.
Vehicles and Business Interests
Retitling a car into a trust can complicate insurance and registration. Tennessee allows transfer-on-death designations on vehicle titles, while Georgia and North Carolina currently do not; in those states you either hold the title in the trust or rely on small-estate procedures, and the Garn St. Germain Act does not extend to vehicle property transfers. Business interests such as LLC membership interests need both a formal assignment and an operating agreement amendment to meet legal requirements for properly moving them into the trust.
The Role of a Successor Trustee in Making This Actually Work
Naming the right successor trustee matters as much as funding the trust correctly. This is the person or institution who takes over trust assets when you die or become incapacitated, without any court involvement.
How a Successor Trustee Avoids Court
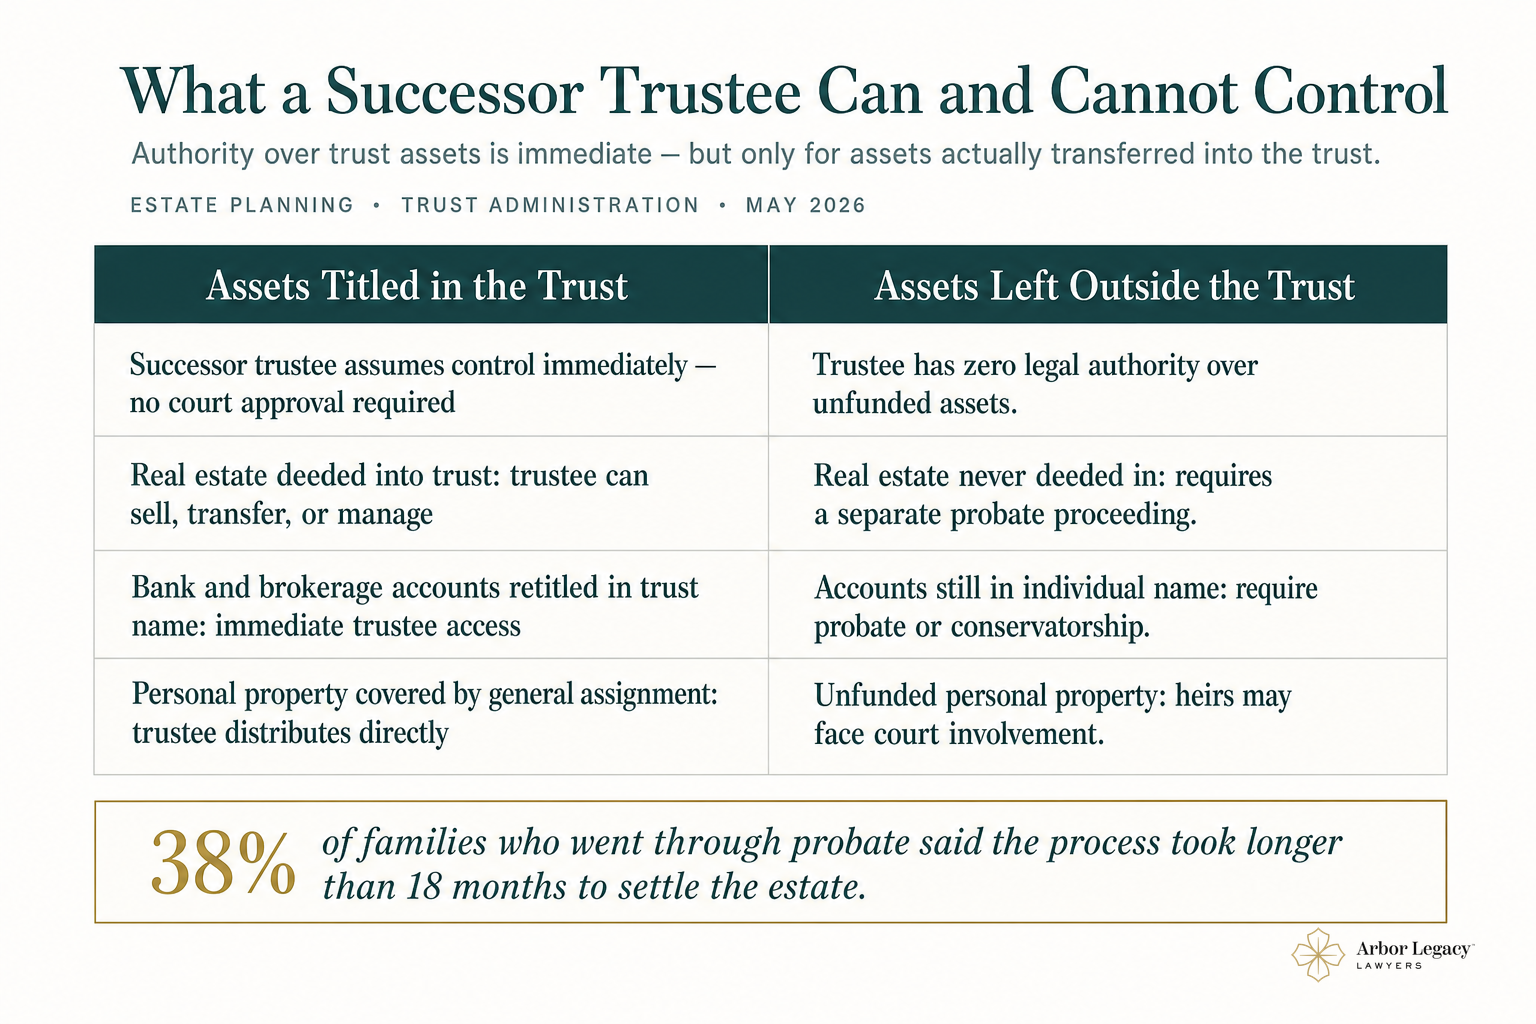
A fully funded trust with a named successor trustee lets your family member manage and distribute assets almost immediately after grantor death, avoiding the months-long wait for a court appointment. Probate typically takes 9 to 24 months nationwide, and in states like California and New York many families see it stretch beyond 18 months Catalina Structured Funding. Name at least one successor trustee and one alternate, and make sure they know where the trust document is kept.
What a Successor Trustee Cannot Do
Even the most capable successor trustee has no authority over assets that were never transferred into the trust. If the house is still in your name at death, the successor trustee cannot take the keys. Funding is what gives your successor trustee something to work with.
When to Consider a Professional Trustee
For complex estates or where family conflict is likely, consulting a financial advisor or professional trustee such as a bank trust department or independent trust company is a neutral option. If family dynamics make the choice complicated, raise it with a qualified estate planning attorney.
When Your Trust Should Be Reviewed and Updated
An estate plan is not a one-time purchase. It evolves as your life does, and reviewing it regularly ensures it continues to serve your estate planning goals, which is the heart of Life & Legacy Planning. Sharing that vision with your family, even through a family mission statement, keeps everyone aligned.
Life Events That Require a Trust Update
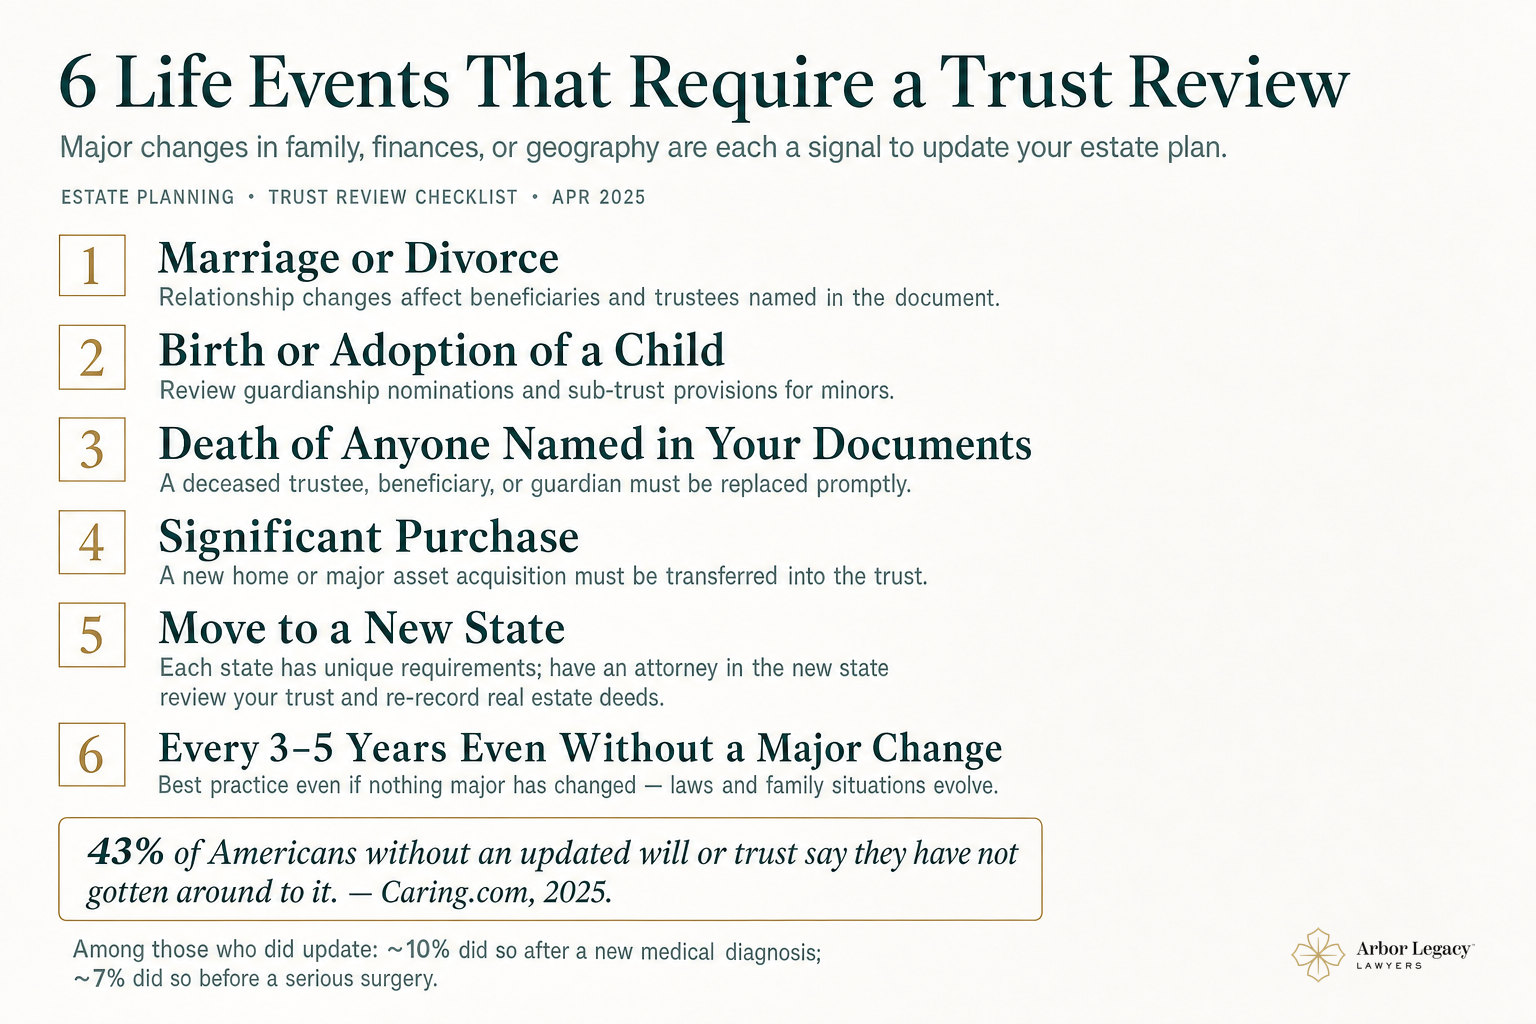
Marriage, divorce, the birth or adoption of a child, the death of a named trustee or beneficiary, a major asset purchase, or a move all warrant a review. In Caring.com's 2025 survey, 30 percent updated their plans after a raise, inheritance, or property purchase, and 23 percent updated to account for births and marriages Caring.com. Procrastination is the real enemy: 43 percent of respondents without a will said they simply "haven't gotten around to it." Review your trust after any major life event and at minimum every three years.
What Happens When You Move to a New State
A trust created in Tennessee is generally valid if you move to Georgia or North Carolina, but property in a new state requires a new deed recorded under that state's rules, and differing probate and estate tax laws make a review worthwhile. Have an estate planning attorney licensed in your new state confirm your trust and deeds comply, and consider seeking legal counsel to review any property transfers triggered by the move.
Kids Protection Planning Deserves Its Own Review
For parents of young children in Williamson County or North Fulton, a trust review is the time to revisit guardianship nominations. A revocable living trust with a sub-trust for minors ensures funds are managed by a trustee you choose, not a court-appointed stranger. This is the core of Kids Protection Planning, and if your spouse isn't on board yet, guardianship nominations and trust funding still belong together as one plan.
Frequently Asked Questions About How to Put Your Assets in a Trust
What is the downside of putting assets in a trust?
Upfront cost, the effort of retitling each asset, and no creditor protection during your lifetime Nolo. For most families, those trade-offs are far outweighed by avoiding probate.
What assets cannot be placed in a trust?
Retirement accounts like IRAs and 401(k)s cannot be retitled into a trust without triggering a taxable distribution Legal Clarity. Health savings accounts and certain annuities also have restrictions. These pass through beneficiary designations.
What is the best way to leave your assets to your children?
A revocable living trust paired with a pour-over will is generally the strongest structure, offering significant benefits including avoiding probate and maintaining control during your lifetime. For a child with a disability, a special needs trust preserves government benefits AARP.
How much does it cost to put all your assets in a trust?
As of 2026, a single person's revocable trust plan generally runs $1,200 to $2,500, and a married couple's plan $2,500 to $4,500 RealCost Report, typically a fraction of the 3 to 8 percent probate can consume.
At what point should you put your assets in a trust?
Now, not after a diagnosis or a death in the family. If you own real estate — including any owned property with a mortgage — have minor children, or run a business, set up a trust while you are alive and well.
Your Next Step Toward Keeping Your Family Out of Court
An unfunded trust is just paper, and paper protects no one. Arbor Legacy Lawyers works with families across Tennessee, Georgia, and North Carolina to create and properly fund revocable living trusts, coordinate beneficiary designations, and build estate plans that evolve as life changes. To explore next steps and common questions about funding your trust, use the link below. To learn which of your assets need to be in a trust and what steps come next, including answers to common questions about beneficial ownership and trust funding, get started with Arbor Legacy Lawyers and schedule a no-pressure planning session.
This article is a service of Arbor Legacy Lawyers P.C. and is provided for educational and informational purposes only. It does not constitute legal advice and does not create an attorney-client relationship. Estate planning laws vary by state; consult a qualified attorney about your specific situation.
Matthew "Web" W. Raulston Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C. Arbor Legacy Lawyers, P.C.