
Key Takeaways
- Accepting a power of attorney role does not make you a co-signer or guarantor on the principal's debts. You use the principal's money to pay the principal's bills, not your own.
- Agents create personal liability mainly three ways: signing documents without noting their agent role, commingling funds, or acting outside the POA document's scope.
- A power of attorney ends the moment the principal dies. Debts then become an estate matter handled by a personal representative through probate.
- Debt collectors may contact you as the authorized representative, but under the Fair Debt Collection Practices Act they cannot claim you personally owe the debt.
- A well-drafted, durable financial POA built inside a complete estate plan is your strongest protection against accidental liability.
Written by Matthew "Web" W. Raulston, Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C. For over 15 years, Web Raulston has been a trusted advisor to individuals, families, and businesses throughout Georgia and Tennessee. A member of the State Bar of Georgia and a father himself, Web focuses on estate planning, business law, and real estate, helping clients protect what matters most through Arbor Legacy's life and legacy planning model.
A daughter in Hixson gets handed a durable power of attorney for her aging father and, sitting at the kitchen table in Hamilton County, wonders whether signing on as his agent means she just agreed to pay his credit card debt and medical bills. That fear is understandable, and questions about principal medical bills and agent responsibility are among the most common that families across Tennessee, Georgia, and North Carolina bring to us. So is power of attorney responsible for debt? The short answer is no. But the exceptions matter, and agents who do not know them can accidentally become personally liable.
This article explains exactly what financial responsibility comes with a durable power of attorney, which actions can create personal liability even when the law does not require it, how debt collectors are allowed to contact you, and what happens to the principal's debts when the principal dies. Getting this right keeps your family out of court and out of conflict — and by the end, you will know precisely where your legal exposure begins and ends.
A Power of Attorney Agent Is Not Personally Responsible for the Principal's Debts by Default
A power of attorney is a legal document that grants authority to act on someone else's behalf. It is not an agreement to absorb their financial obligations. When you act as an agent, you use the principal's money and exercise the principal's authority, so no new debt attaches to you personally.
The Agent Acts as a Representative, Not a Co-Borrower
Think of a POA agent like an employee making purchases on a company card. The employee is not the debtor. The company is. When you pay a bill, use a principal bank account, or manage real property on the principal's behalf, you draw on principal funds and act in the principal's name. Tennessee law — and similar laws in Georgia and North Carolina — treats agents as trusted managers, not guarantors (Tenn. Code Ann. § 34-6-101 et seq.; each state has adopted its own version of the Uniform Power of Attorney Act). In all three states, agents are treated as fiduciaries rather than guarantors. As of January 2026, 31 states plus the District of Columbia follow the Uniform Power of Attorney Act, which codifies explicit fiduciary duties across those jurisdictions. This same principle is recognized across the country — for additional context, Ohio's statute (Ohio Rev. Code § 1337.092) spells out the same four exceptions: personally guaranteeing the debt, owing an independent duty of support, acting negligently, or exceeding authority.
What Acting on the Principal's Behalf Actually Means
Agents commonly handle financial matters such as bank accounts, real estate transactions, bill payment, and investment decisions. Every one of these draws on principal money, not agent money. The POA document itself defines the scope of your authority, so read it carefully. Authority that is not listed is authority you do not have. If you are helping a parent set up a power of attorney, understanding this scope is the first step.
Why This Protection Exists Under Fiduciary Law
Your duty to act as a fiduciary runs toward the principal, not toward creditors. You must act in the principal's best interest, which includes managing debts responsibly, but that duty never transforms into personal financial responsibility. Your job is to manage the principal's money wisely, not to cover the principal's debts with your own. As many families learn, a power of attorney may not be what you think it is, which is exactly why the scope of your duty matters.
Three Situations Where an Agent Can Become Personally Liable
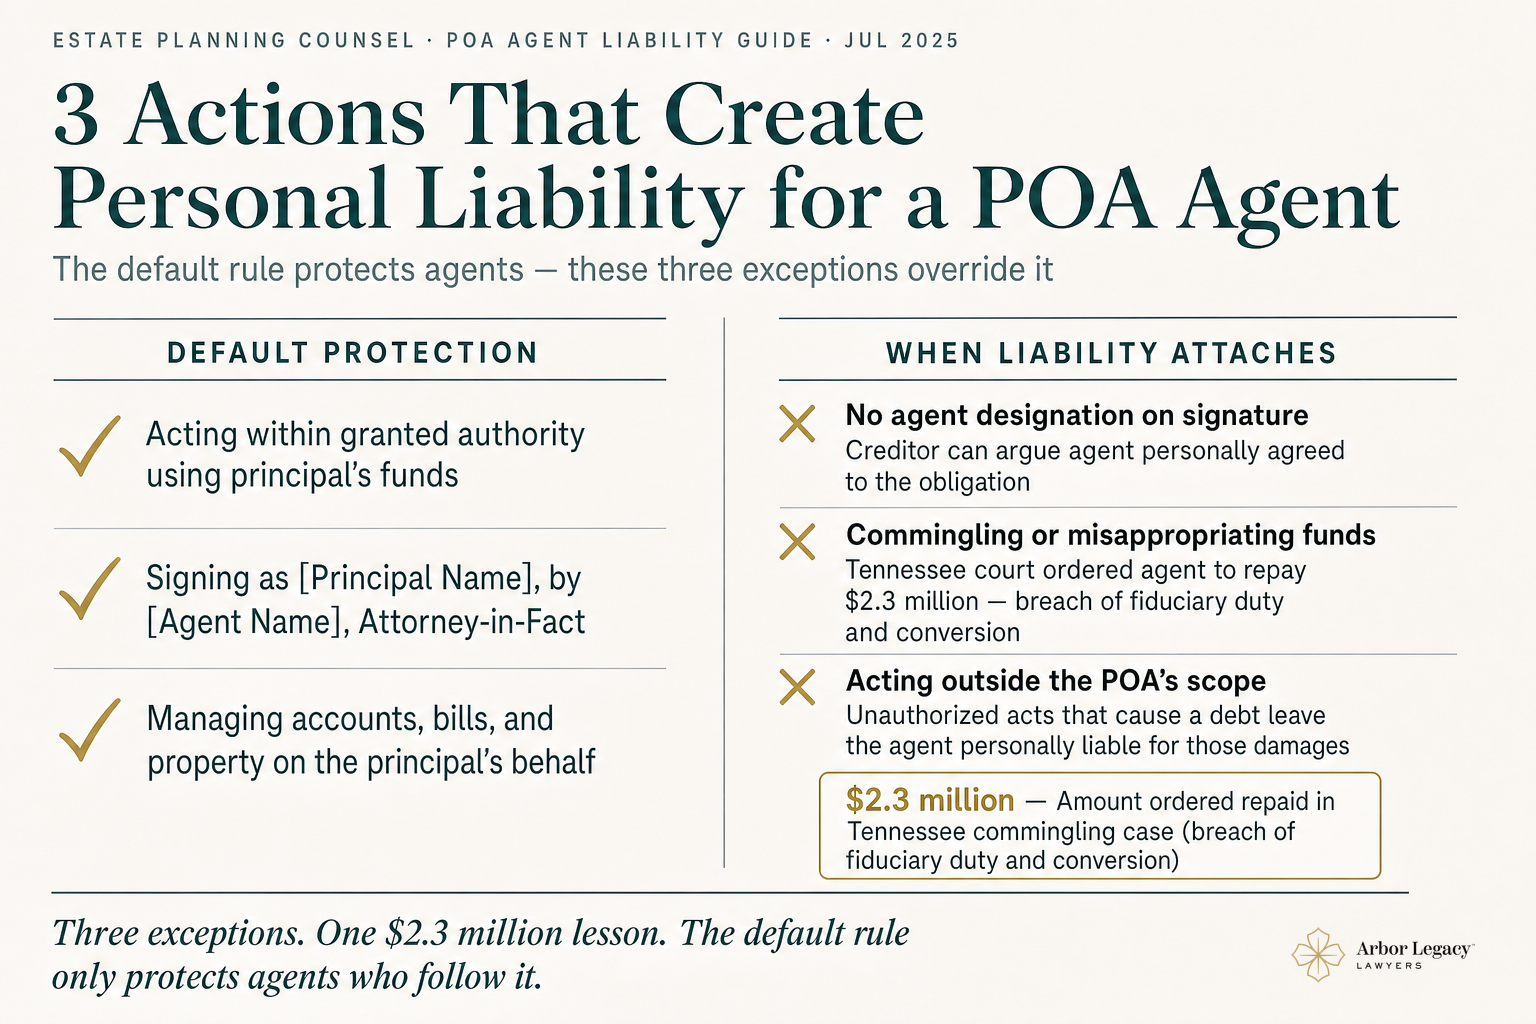
The general rule protects you, but three real exceptions trip agents up. These are the highest-stakes mistakes to avoid, and each one is entirely preventable once you know the pattern.
Signing Documents Without Identifying Your Role as Agent
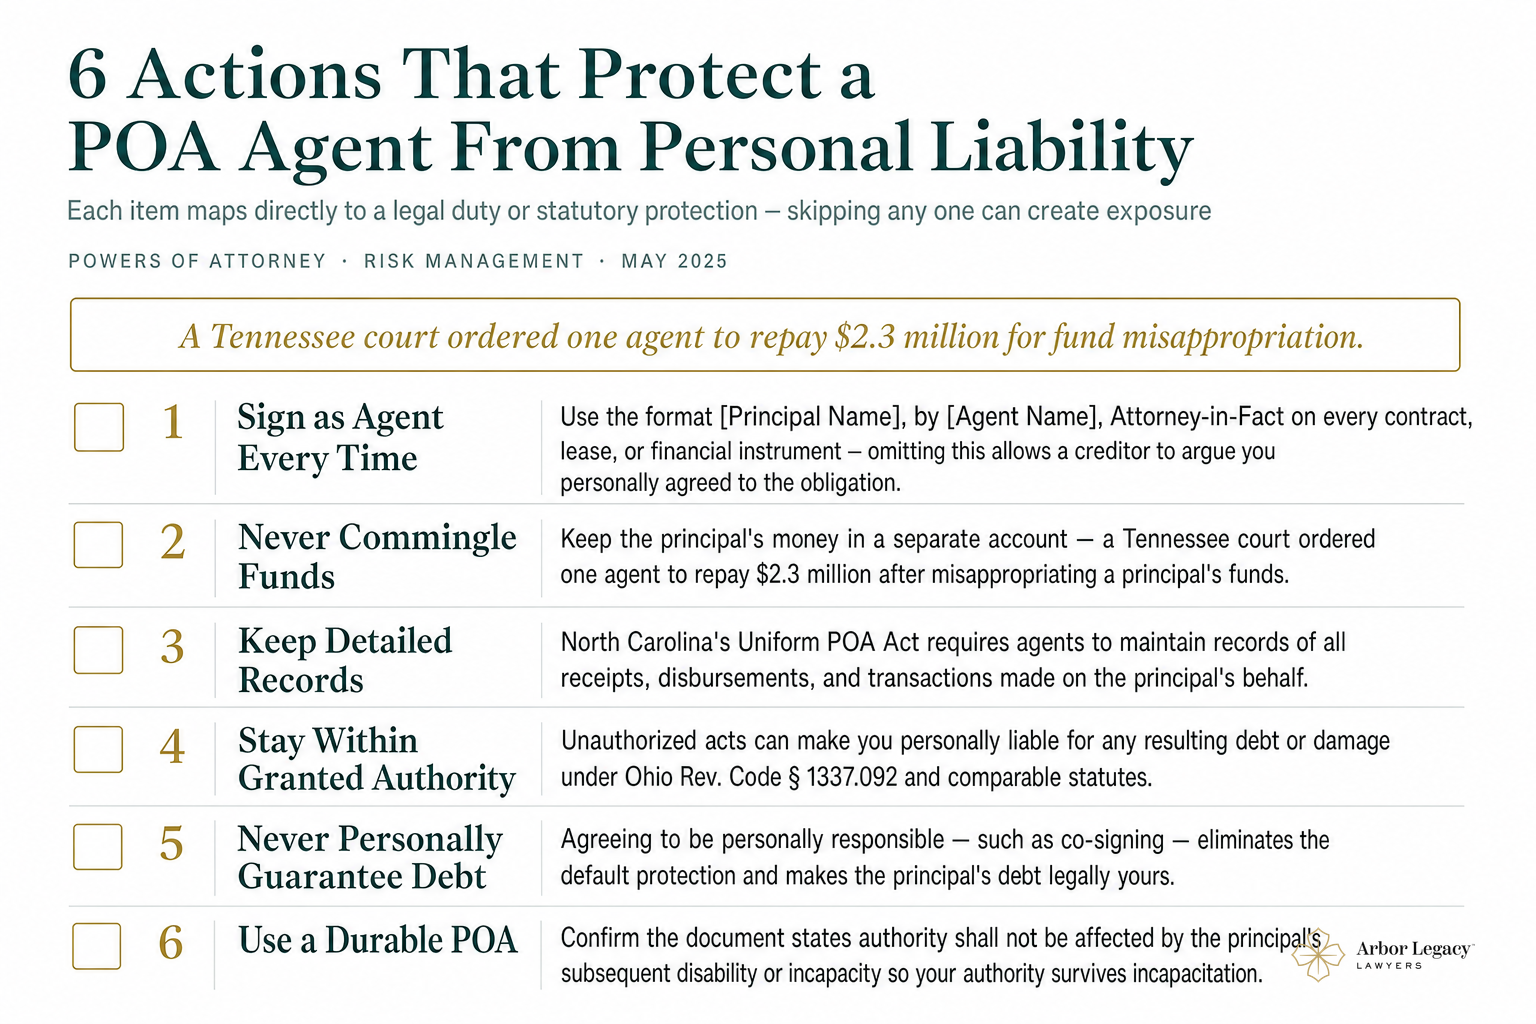
If you sign a contract, lease, or credit application without noting that you are signing as agent, a creditor can argue you personally agreed to the obligation. Sign it this way every time: "[Principal Name], by [Agent Name], Attorney-in-Fact." In a 2025 New York case involving a 2024 contract, an agent who signed purely on the principal's behalf was not personally bound because the contract contained no personal promise. Your agent designation belongs on every document you sign, every single time.
Mixing the Principal's Funds With Your Own Money
Depositing principal money into your personal account or spending principal funds on yourself breaches your fiduciary duty. In one Tennessee case, an agent who misappropriated an elderly principal's money was ordered to repay approximately $2.3 million for breach of fiduciary duty and conversion. Keep a separate account and clear records for all principal funds. Commingling is never worth the risk.
Acting Outside the Scope of the POA Document
If you take a financial action the POA document does not authorize, such as making property transfers when only financial matters are granted, that action can be voided and you can be held personally responsible for the resulting harm. The Ohio statute expressly imposes liability where an agent's unauthorized act causes a loss. When in doubt about whether an action is authorized, stop and consult an attorney before proceeding.
The checklist below summarizes these three liability triggers and how to avoid each one.
What Happens to the Principal's Debts When the Principal Dies
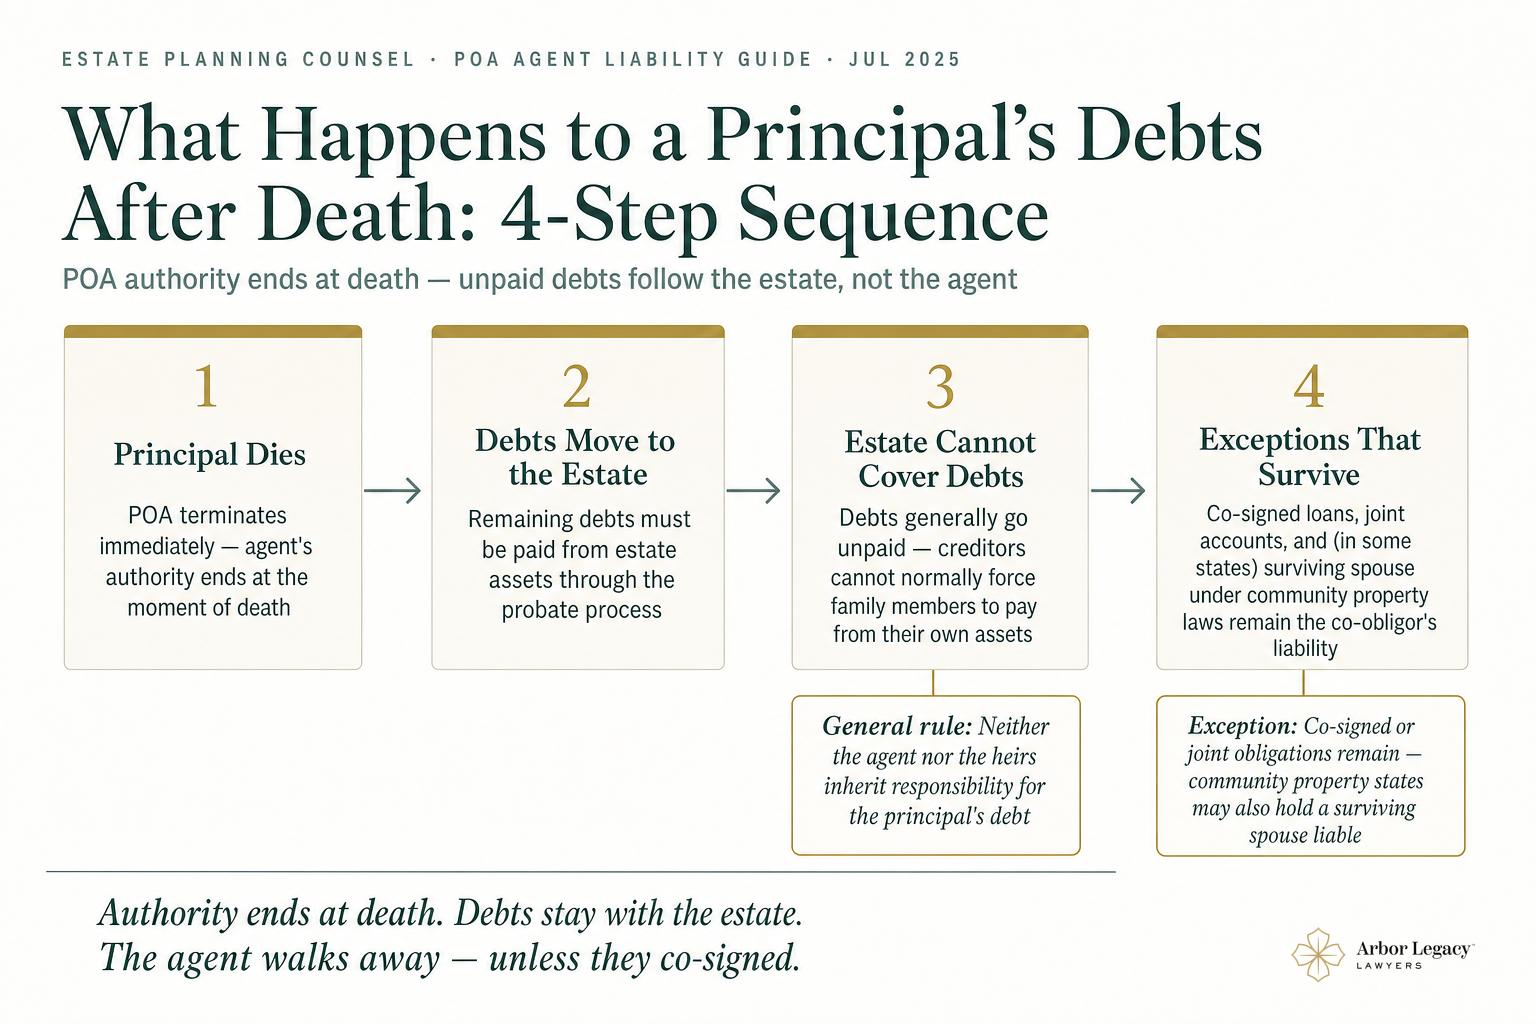
A power of attorney ends at the moment of the principal's death, and so does your authority. What happens to unpaid debts after that is an estate law question, not a POA question. Many families confuse the two.
The Power of Attorney Terminates the Moment the Principal Dies
Even a durable financial POA that survives incapacity does not survive death. Under Tennessee's Uniform Durable Power of Attorney Act and general agency law, the agency terminates at the principal's death. Any financial action you take under the POA after the principal death is unauthorized and potentially fraudulent. If your loved one passes away, stop acting under the POA immediately and notify the relevant financial institutions.
Who Actually Pays the Principal's Debts After Death
After the principal death, debts become a matter for the estate, managed by a personal representative through probate. Principal debts and creditor claims are paid from estate assets in a legally specified order before any inheritance is distributed. If the estate lacks funds, most debts go unpaid, because the Consumer Financial Protection Bureau confirms no one else generally has to pay a deceased person's debts from their own money, subject to limited state-specific exceptions. The four-step sequence follows a predictable path. The POA ends at death, an executor or administrator is appointed, creditor claims are paid from estate assets, then heirs receive what remains. The one exception is shared obligations. A co-signed loan or joint account holder stays liable.
Community Property and Surviving Spouse Considerations
Tennessee, Georgia, and North Carolina are not community property states, so a surviving spouse generally does not inherit a deceased spouse's sole debts unless the debt was joint or for necessities. This distinction matters for any family member who relocated from a community property state. If you moved to the North Georgia mountains or Williamson County from one, review pre-existing debt obligations with an estate planning attorney.
How Debt Collectors Can and Cannot Contact a Power of Attorney Agent
Debt collectors reach out to agents because you are the accessible point of contact. You need to know your rights and what you are never obligated to do.
The Fair Debt Collection Practices Act Protects Agents Too
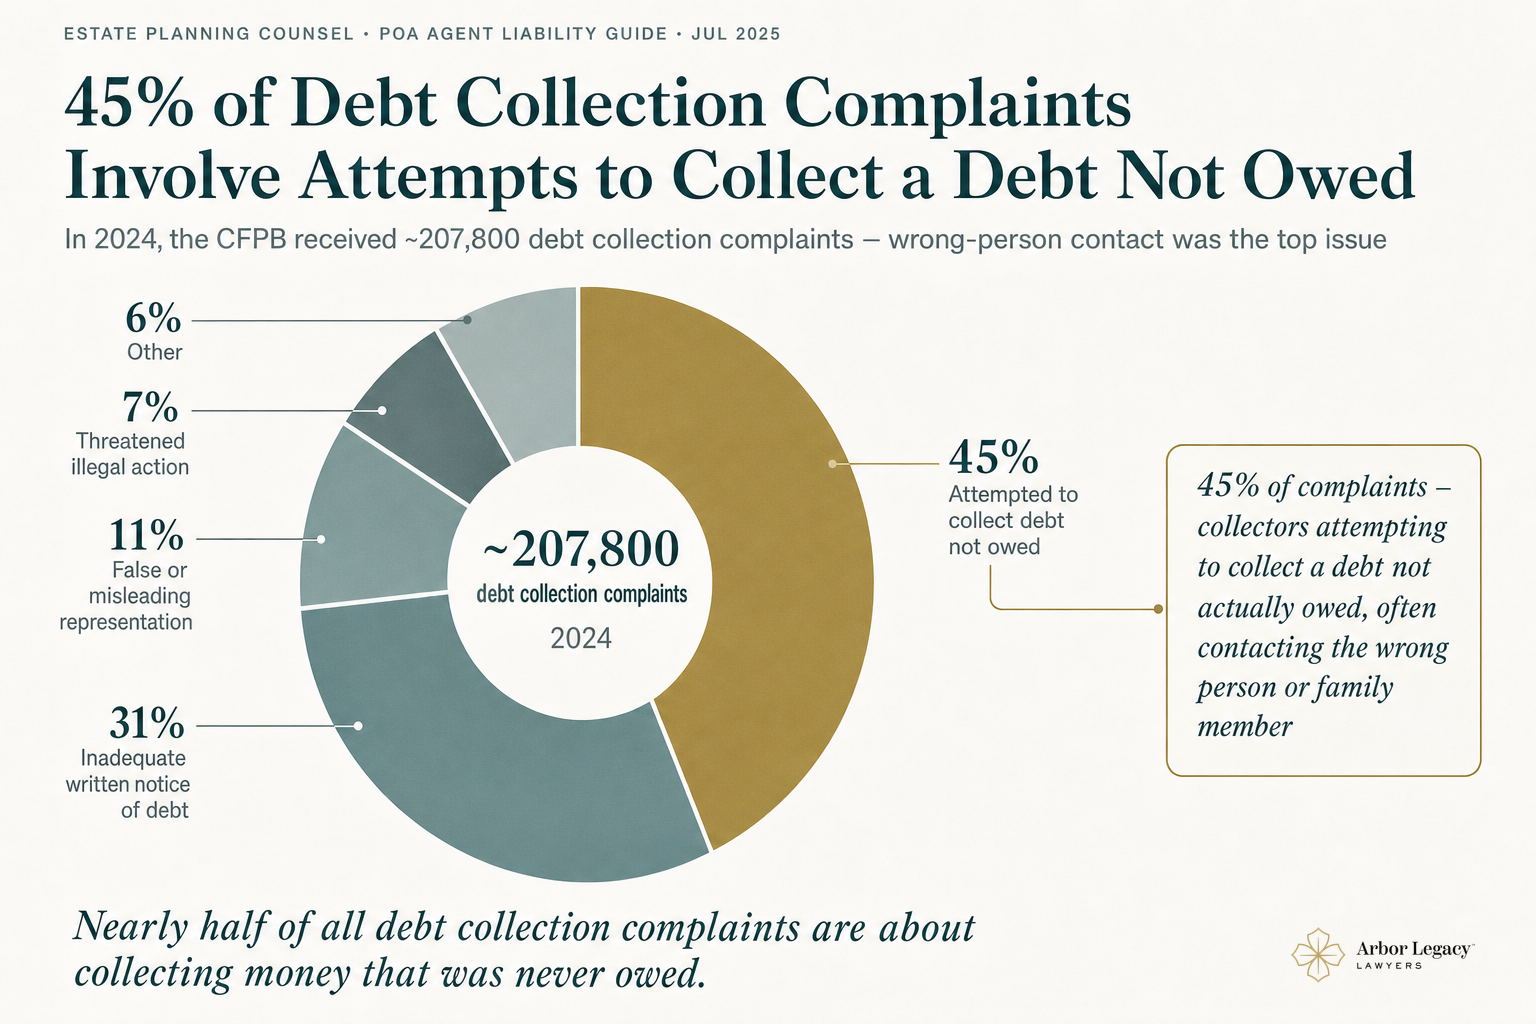
The Fair Debt Collection Practices Act governs what a debt collector can say and do. A collector cannot misrepresent that you personally owe the debt, threaten action they cannot take, or use abusive tactics. They generally cannot call before 8 a.m. or after 9 p.m. or harass you with repeated calls. Debt collection remains a top consumer complaint. In 2024 the CFPB received roughly 207,800 debt collection complaints, and about 45% involved attempts to collect a debt the consumer reported was not owed. If a collector tells you that you personally owe the principal debt, document it and consult an attorney.
What Agents Are and Are Not Obligated to Tell Creditors
You have authority to communicate with creditors, negotiate payment arrangements using principal funds, and provide updated mailing addresses for billing. You are not obligated to pay a credit card company or other creditors from your own money or accept calls outside reasonable hours. Communicate from your position of authority, not from personal obligation.
When Communicating With Creditors, Clarity Protects You
Every written communication should identify you by name, state your role under the POA, and reference the POA document enough to establish authority. Begin verbal conversations the same way. This paper trail protects you if disputes arise. Start with: "I am contacting you in my capacity as agent under a durable power of attorney for [Principal Name]."
The Agent's Core Financial Duties and How Staying Within Them Prevents Liability
Responsible day-to-day management is what keeps you protected. These habits, more than any legal technicality, prevent accidental missteps.
Record-Keeping Is Not Optional, It Is Your Best Defense
Keep a written log of every transaction made on the principal behalf, date, amount, account used, purpose, and authorization. North Carolina's Uniform Power of Attorney Act requires agents to keep records of all receipts, disbursements, and transactions, act loyally for the principal's benefit, and avoid conflicts of interest. If your decisions are ever challenged by family members or a court, clear records are the difference between a resolved dispute and personal liability. Treat the principal's finances like a business you are managing. This kind of documentation discipline is one reason estate documents fail when they are left to chance rather than built with guidance.
Prioritizing the Principal's Best Interest Over Family Pressure
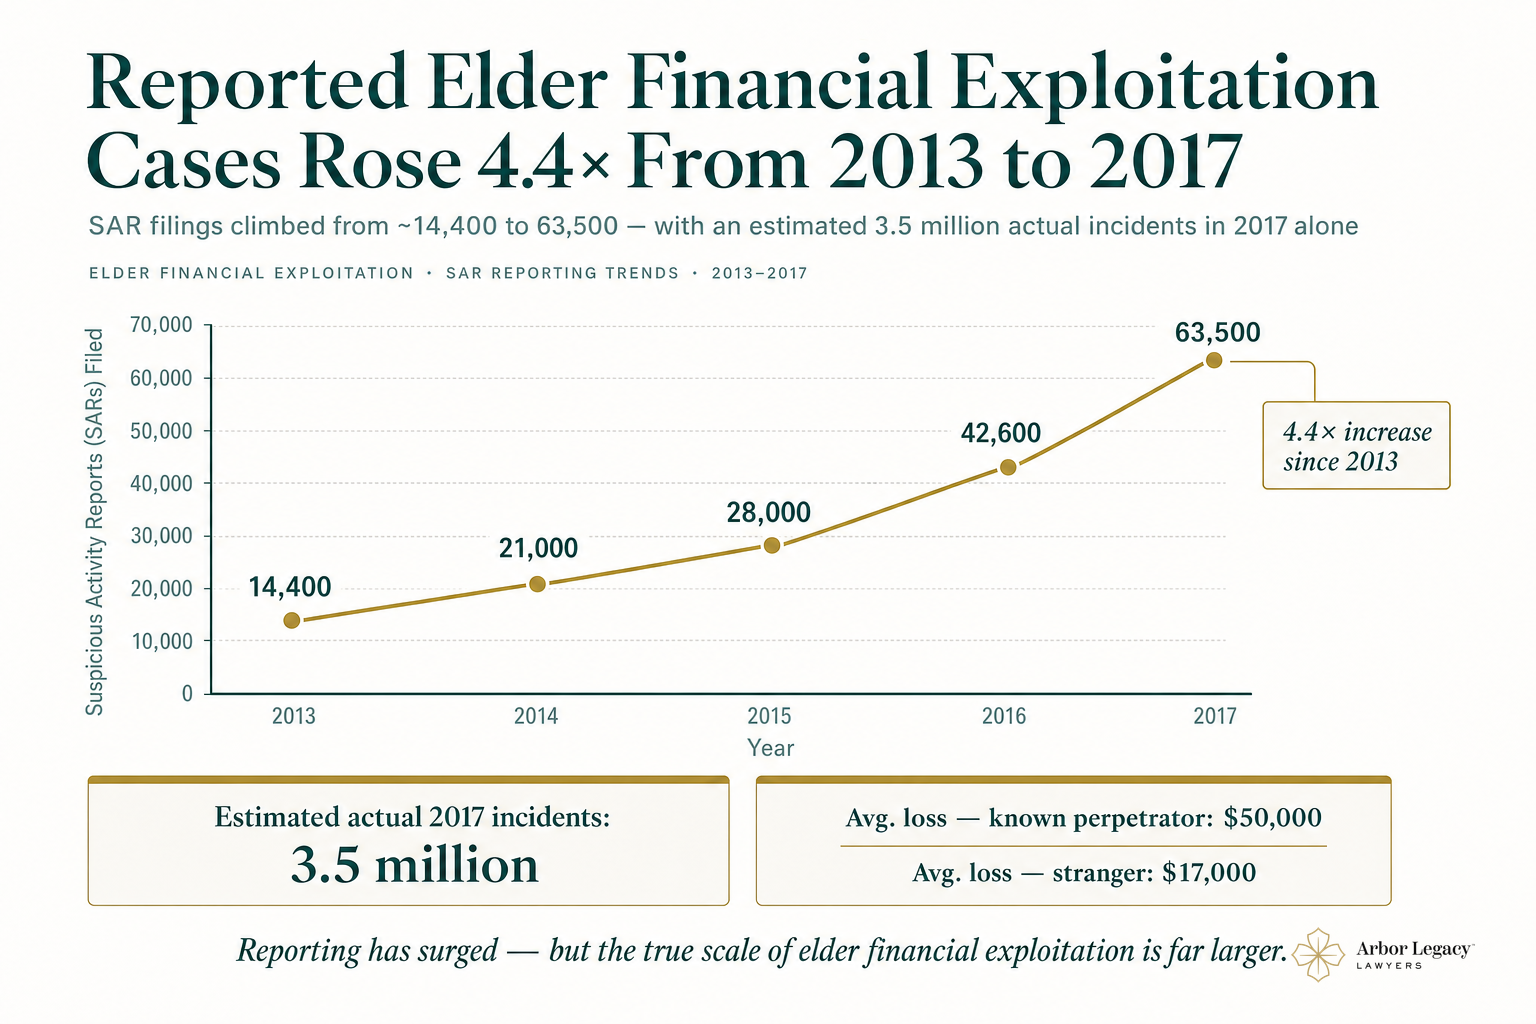
Agents often feel pressure from relatives to pay certain bills first, make gifts, or transfer assets. The legal standard is the principal best interest, not what the family prefers. This matters because elder financial exploitation, often carried out through misuse of a POA, has surged. The CFPB found that elder financial exploitation Suspicious Activity Report filings quadrupled between 2013 and 2017, reaching 63,500 reports in 2017 and involving more than $6 billion in transactions over that period. Document any significant decision and be able to explain why it served the principal.
When to Involve an Attorney Before Acting
Some financial matters, such as real estate transactions, business dealings, and large asset transfers, are complex enough that you should not act alone. The cost of a consultation is always less than the cost of a mistake that creates personal liability or triggers legal issues down the road. Our attorneys work with agents navigating these situations across Tennessee, Georgia, and North Carolina, from Chattanooga and Franklin to Alpharetta, Trenton, and Blue Ridge — all five of our office locations. We also help families with related needs including elder law planning, asset protection planning, and kids protection planning — because a POA rarely exists in isolation. If a decision feels uncertain, pause and get legal guidance before signing anything.
How a Well-Drafted POA Document Reduces Agent Risk From the Start
Many agent liability problems trace back to a vague or generic POA document. Getting the legal document right at the outset is the cleanest way to protect everyone involved.
What a Financial POA Document Should and Should Not Include
A solid durable power of attorney defines the scope of your authority, specifies which financial matters are covered, addresses whether you can make gifts, and sets out limitations. Modern laws adopted in over 30 states require that certain powers, such as making gifts or changing beneficiaries, be expressly granted. Generic online forms leave these elements vague and create disputes. Choosing the right estate planning documents up front prevents that. A vague POA protects no one.
Durable vs. Non-Durable and Why It Matters
A standard POA terminates if the principal becomes incapacitated. A durable power of attorney remains in effect precisely when it is needed most. Tennessee law defines a durable POA as one stating it shall not be affected by the principal's subsequent disability or incapacity. If your POA does not say durable, it may not work when you actually need it. A durable financial power of attorney is one of the best estate planning documents for exactly this reason.
Why POA Planning Belongs Inside a Complete Estate Plan
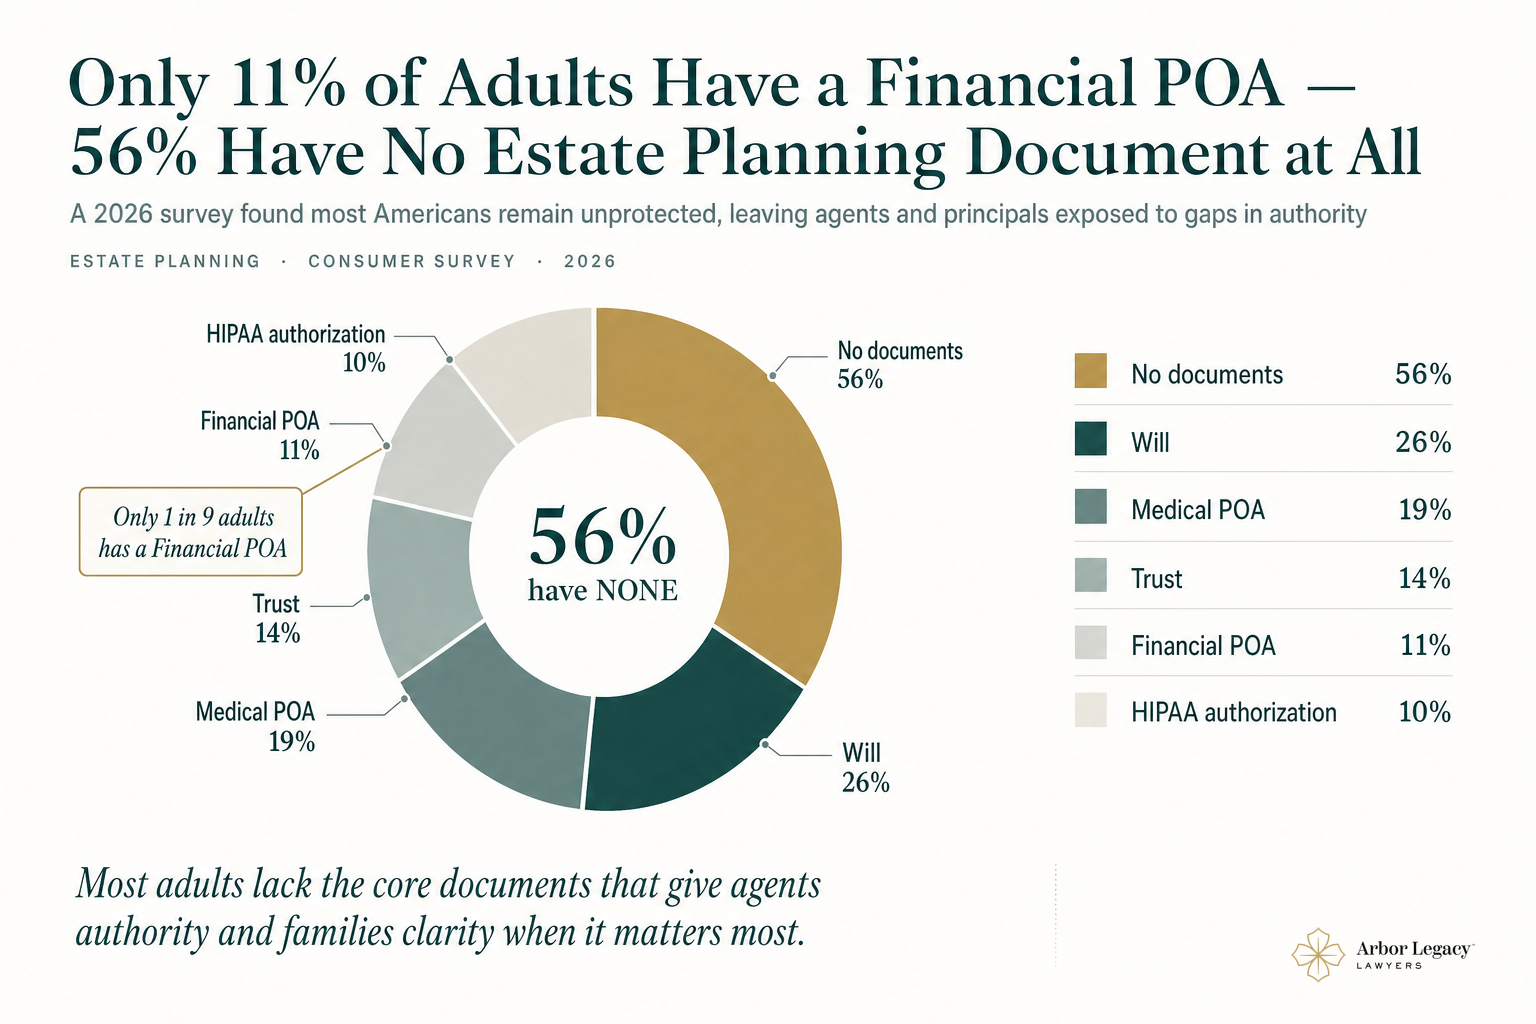
A financial POA is one piece of a broader plan that includes a health care power of attorney or directive, a will or trust, and beneficiary designations — and when done well, that plan also captures the values, family stories, and relationships the principal wants to preserve, not just the financial authority. Yet only about 11% of adults have a financial power of attorney, and 56% have no estate planning document at all, according to a 2026 Trust & Will survey of 5,000 U.S. adults. When these documents work together, they minimize court interference and give agents clear authority. A standalone POA without a full plan leaves gaps for agents and families alike. If your parents are aging, these are three estate planning documents your parents need right now.
Frequently Asked Questions: Is Power of Attorney Responsible for Debt
What are the liabilities of being a power of attorney?
Your personal liability is limited to situations where you step outside your role, signing documents without identifying yourself as agent, commingling personal and principal funds, acting beyond the POA document's scope, or continuing to act after the principal's death. Within those boundaries, agents are generally protected from the principal's debts.
Am I responsible for my parent's debt if I have power of attorney?
No. Holding a financial power of attorney over a parent's finances does not make you responsible for their debts. You manage their money and pay their bills using their funds, and you are not a co-signer or guarantor. The only debt you would owe is a debt you were already jointly liable for, such as a joint credit card account.
What is the downside of being a power of attorney?
The role carries real responsibility and scrutiny, record-keeping, acting in the principal's best interest at all times, communicating with creditors, and making difficult decisions under family pressure. Mistakes, even well-intentioned ones, can create personal liability, and a court can remove an agent who breaches their duties.
Does having power of attorney make you financially responsible?
Having a financial power of attorney makes you responsible for managing someone else's finances carefully. It does not make you financially responsible for their debts. Responsibility to manage is not the same as responsibility to pay, as long as you sign as agent and stay within your authority.
Can debt collectors come after power of attorney agents?
A debt collector can contact you as the authorized representative for the principal, but cannot legally claim you personally owe the debt. Under the Fair Debt Collection Practices Act, misrepresenting a person's liability is prohibited. If a collector states or implies you personally owe the principal's debt, you can report it to the CFPB and consider legal action against the collector.
What Agents Should Do Next to Protect Themselves and the People They Love
The good news is that most agents who understand their role never face personal liability at all — and the families they are trying to help stay out of court and out of conflict. A well-drafted legal document makes that outcome entirely achievable.
Arbor Legacy Lawyers helps families across Tennessee, Georgia, and North Carolina create durable powers of attorney and complete estate plans that give agents clear authority, defined boundaries, and real legal protection. For families with minor children, a complete plan also includes Kids Protection Planning to ensure your children are raised by the people you choose, without court interference. A POA is not a form to download from the internet. It is part of an ongoing Life & Legacy Planning relationship that grows and evolves with your family through every life stage — a new child, a health change, a move, a business — not a one-time transaction — and it should be built carefully with an attorney who knows your whole picture.
The best time to get this right is before a crisis, not during one. This kind of careful, relationship-based planning has traditionally been available only to high-net-worth families, but Arbor Legacy Lawyers makes it accessible to every family with transparent, no-surprise pricing. Schedule a Life & Legacy Planning Session with Arbor Legacy Lawyers to review or create a financial POA that protects everyone involved, agents, principals, and your whole family. Get started with Arbor Legacy Lawyers today.
This article is a service of Arbor Legacy Lawyers P.C. and is provided for educational and informational purposes only. It does not constitute legal advice and does not create an attorney-client relationship. Estate planning laws vary by state; consult a qualified attorney about your specific situation.
Matthew "Web" W. Raulston
Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C.
Arbor Legacy Lawyers, P.C.