
Key Takeaways
- Many revocable trusts are never properly funded, which is why families who believe they avoided probate often still end up in court after a death.
- Funding means retitling assets into your trust’s name, or naming the trust as beneficiary for assets like life insurance and retirement accounts.
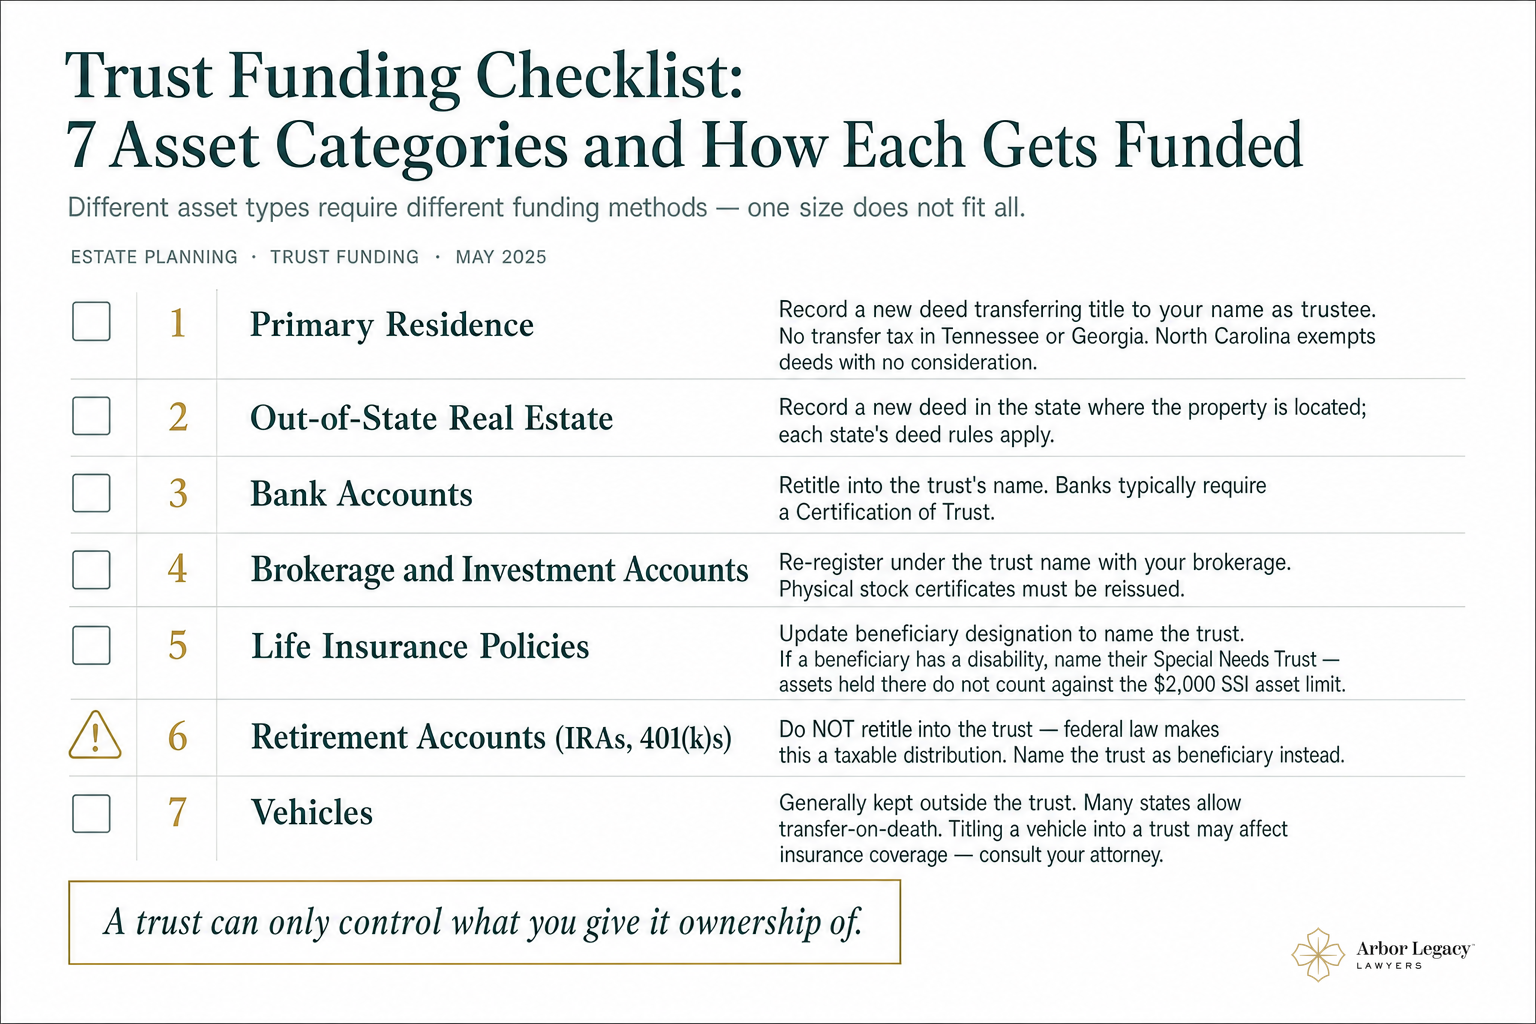
- Real estate, bank accounts, and brokerage accounts get retitled. Retirement accounts and life insurance policies use beneficiary designations instead.
- A funded trust protects you during incapacity too, letting your successor trustee act immediately without court-supervised guardianship.
- Every new asset you acquire must be deliberately funded, which is why an estate plan is an ongoing relationship.
Get insights like this in your inbox
Written by Matthew "Web" W. Raulston, Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C. For over 15 years, Web Raulston has been a trusted advisor to individuals, families, and businesses throughout Georgia and Tennessee. A member of the State Bar of Georgia and a father himself, Web focuses on estate planning, business law, and real estate, helping clients protect what matters most through Arbor Legacy's life and legacy planning model.
Imagine a family who loses a parent and then discovers that the revocable living trust he signed years earlier was never funded. The house, his bank accounts, his brokerage account, all still titled in his individual name. Everything goes through probate court anyway. Understanding what is funding a trust is the difference between a plan that works and an empty container that fails your family when they need it most. This article explains what funding means, which assets to move and how, what happens when families skip this step, and what to do if your trust may not be fully funded.
A Trust Without Funding Is Just a Piece of Paper
What Is Funding a Trust: What It Actually Means
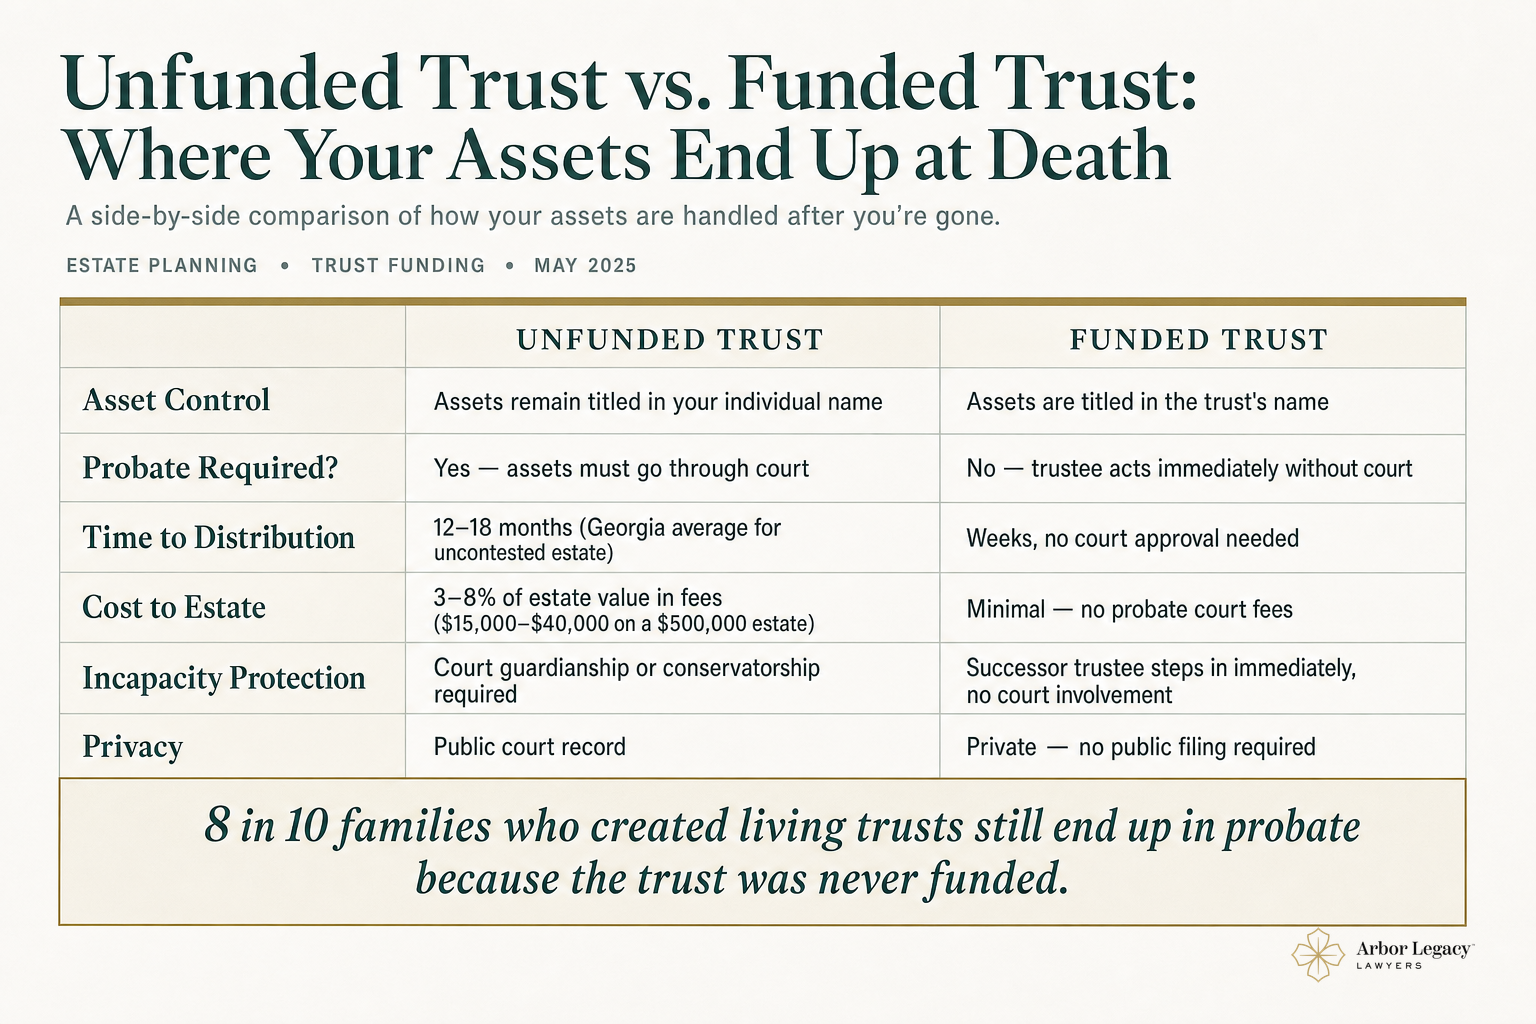
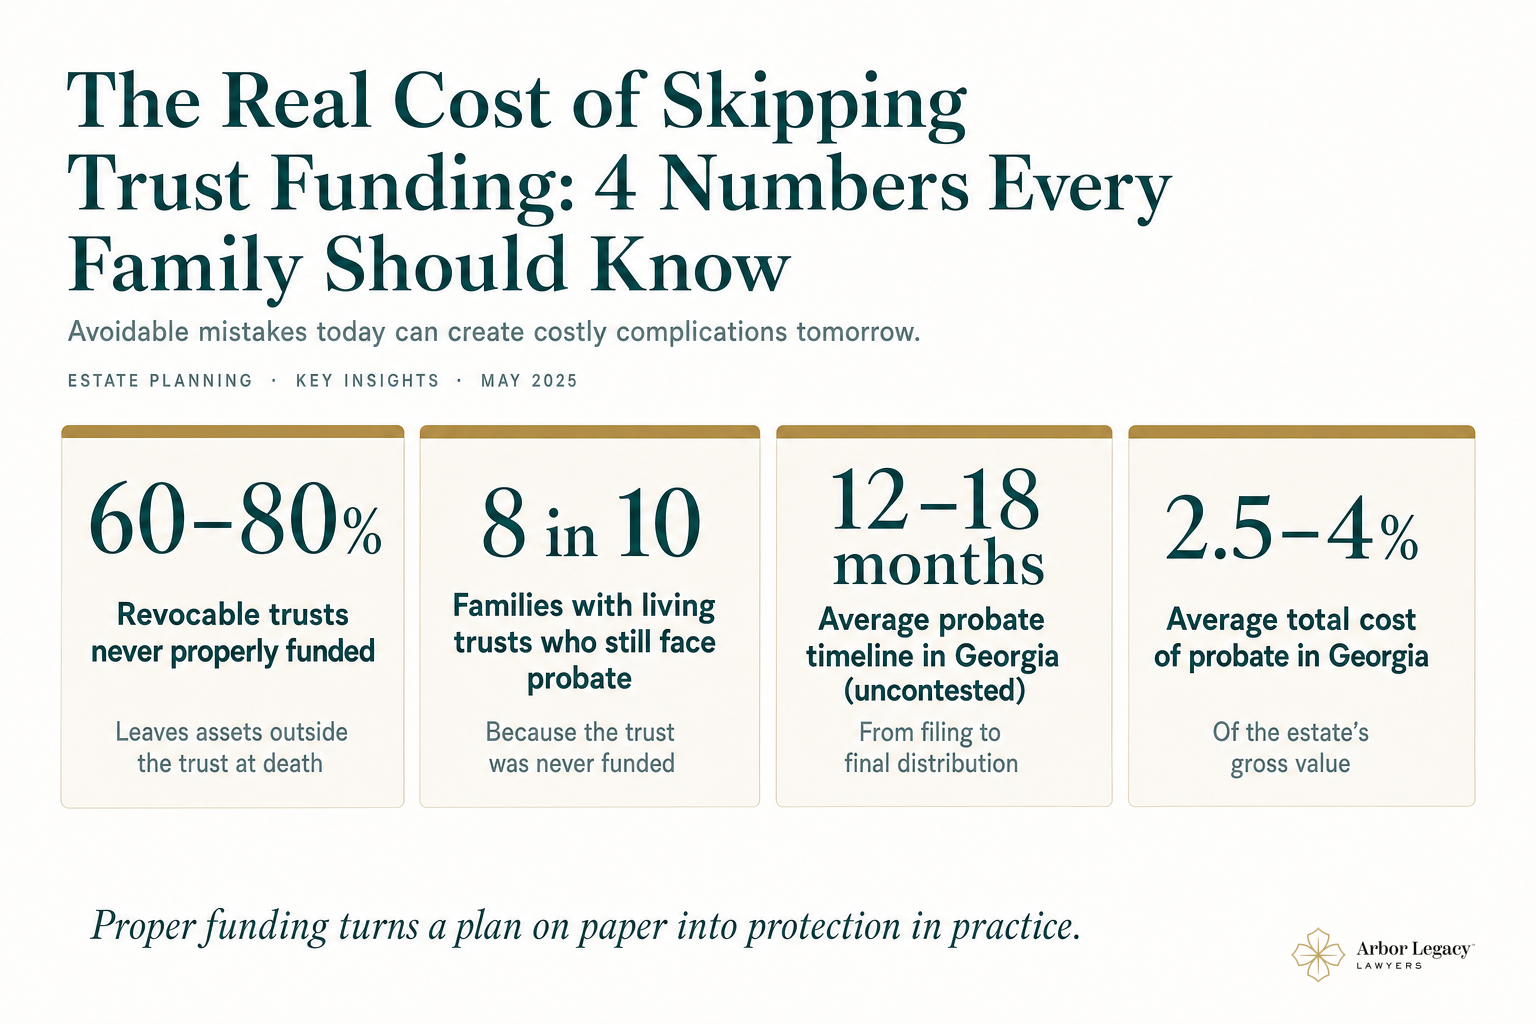
Funding a trust means legally transferring ownership of your assets from your individual name into the name of your trust, or naming the trust as beneficiary where a direct transfer is not possible. Used correctly, a funded trust is a powerful estate planning tool for protecting your family. The trust agreement is the set of rules, the trust assets give those rules something to govern, and the legal document itself must be properly executed before funding begins. Enduring Legacy Mentors estimates that around 80 percent of trusts are never funded, a practitioner figure rather than a formal study, per Enduring Legacy Mentors. Check whether each major asset is titled in your name or your trust's name. If you are weighing options, our overview of creating a trust in your will versus creating a living trust is a helpful starting point.
Why Retitling Is the Core Action
Retitling means changing legal title on real property, bank accounts, and investment accounts so the trust is listed as owner, replacing any prior joint ownership arrangement. For life insurance and retirement accounts, funding means updating the beneficiary designation instead. Readers commonly confuse ownership transfer with beneficiary designation, and the difference matters. Different asset types and different types of trusts follow their own rules, and living trusts in particular require careful attention to retitling. If you are still deciding, our guide on whether a revocable living trust or an irrevocable trust is right for you breaks down the tradeoffs.
What Happens to Your Family When a Trust Is Not Funded
The Probate Problem
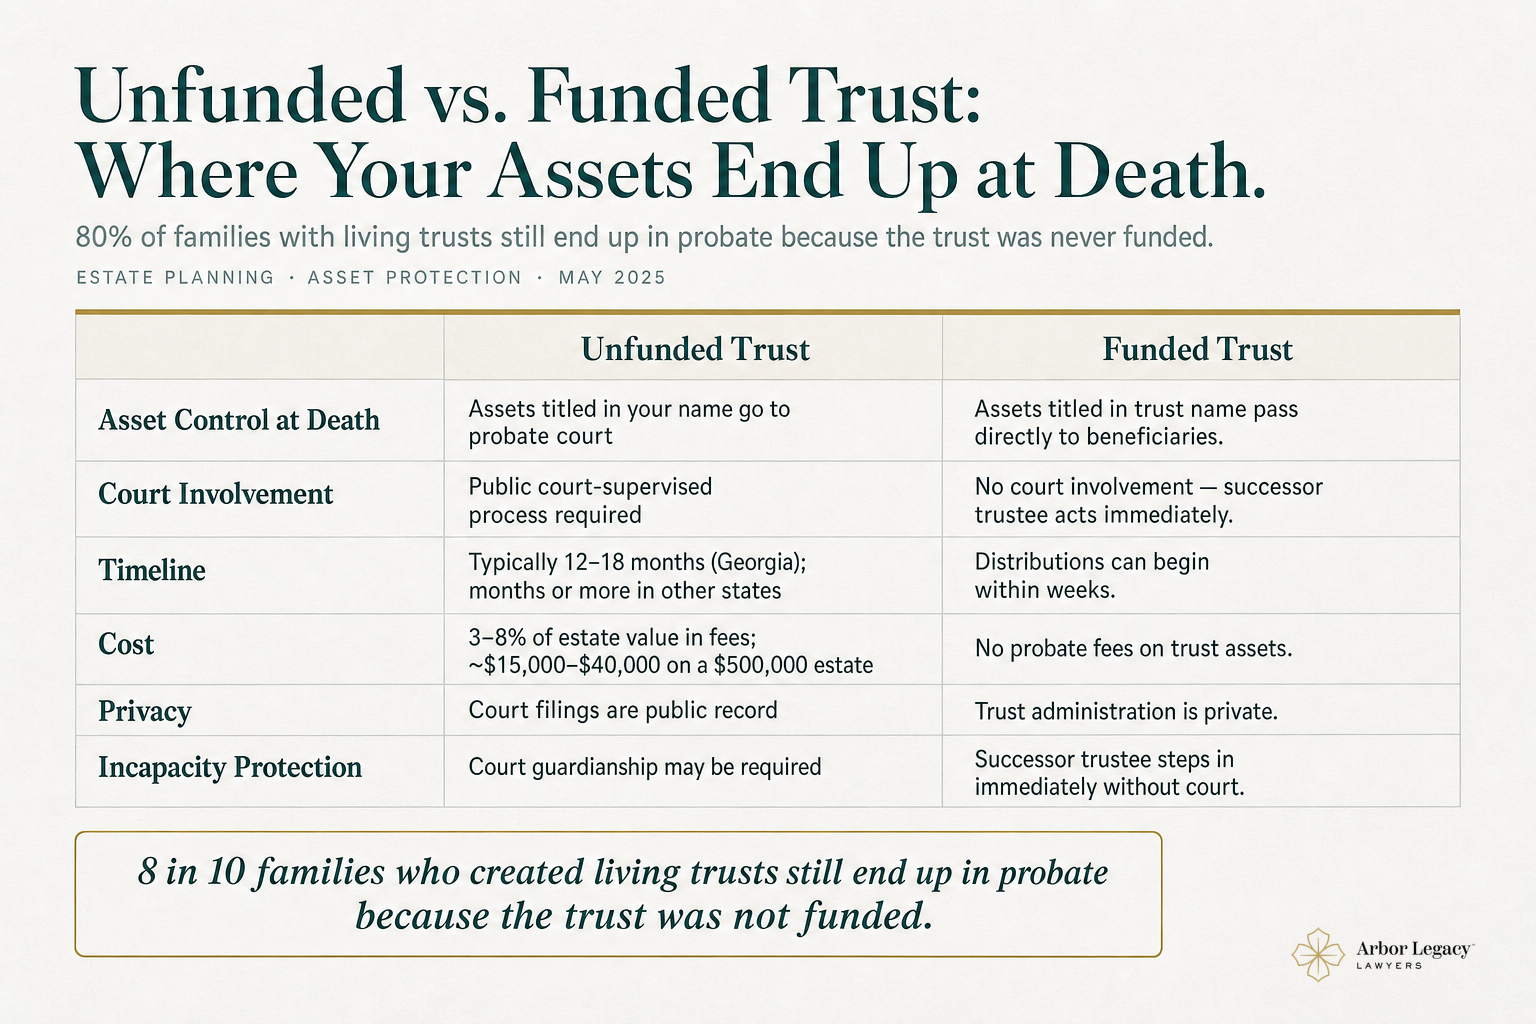
Assets left outside your trust must go through probate despite the trust's existence. Probate in Tennessee, Georgia, and North Carolina is a public, court-supervised process. Most uncontested Georgia estates take roughly six months to a year, according to Scriber Law Group. Costs typically run 3 to 8 percent of an estate's value per Settled Estate, which can mean $15,000 to $40,000 on a $500,000 estate. Only about 51 percent of adults 50 and older even have a will, according to AARP research. Our piece on why putting your family home in a trust is a smart move walks through how funding your residence keeps it out of that process.
What Out of Court and Out of Conflict Really Requires
A trust's promise of keeping loved ones out of court and out of conflict depends entirely on funding. When assets are missing, family members can disagree about what was intended. In an Ameriprise survey of 2,700 people, about 1 in 4 said an inheritance caused tension, and a separate study reported by InvestmentNews found 58 percent experienced family disputes and assets falling under court control when planning was inadequate. The document alone does not protect your family. The funding does.
Which Assets Go Into a Trust and Which Stay Outside
Assets That Should Be Retitled Into the Trust
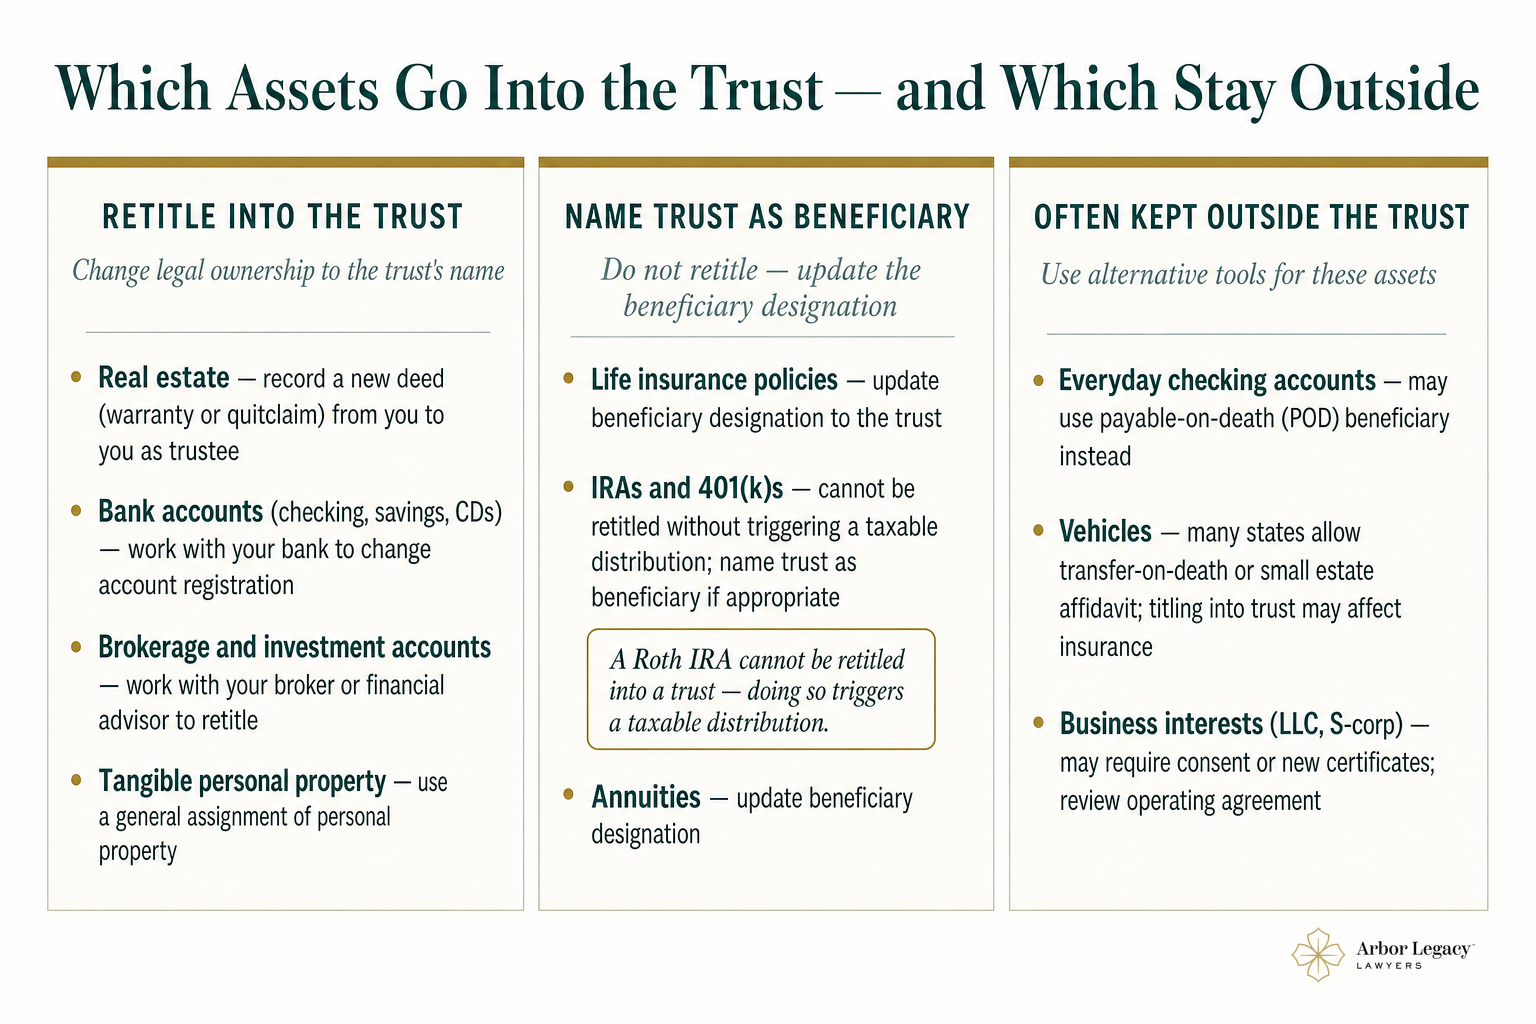
Real estate is usually the highest-value asset and the most important to retitle through a new deed, including out-of-state property. Bank and brokerage accounts get retitled by working directly with the financial institution. Tangible personal property such as vehicles, collections, and personal effects can often be transferred using a general assignment of personal property. Start with real estate and primary financial accounts, since these have the biggest impact on probate avoidance.
Assets That Use Beneficiary Designations Instead
Life insurance policies and retirement accounts generally should not be retitled into a trust. Federal law requires IRAs to be owned by an individual, so retitling one triggers a taxable distribution, per Legal Clarity. The usual strategy is to name the trust as beneficiary. Special needs planning creates an exception, for a beneficiary with disabilities, name a Special Needs Trust as beneficiary to protect Medicaid eligibility. To keep a child's inheritance protected long term, see how a lifetime asset protection trust can shield what you pass on.
Assets That Generally Stay Outside the Trust
Some assets are better left out. A small everyday checking account often works better with a payable-on-death designation. Vehicles and other motor vehicles in some states create insurance complications when retitled. Certain business interests carry their own succession structure. An irrevocable trust follows different funding rules than revocable trusts, so confirm which category each asset belongs in.
How Funding a Trust Actually Works Step by Step
The Real Estate Transfer Process
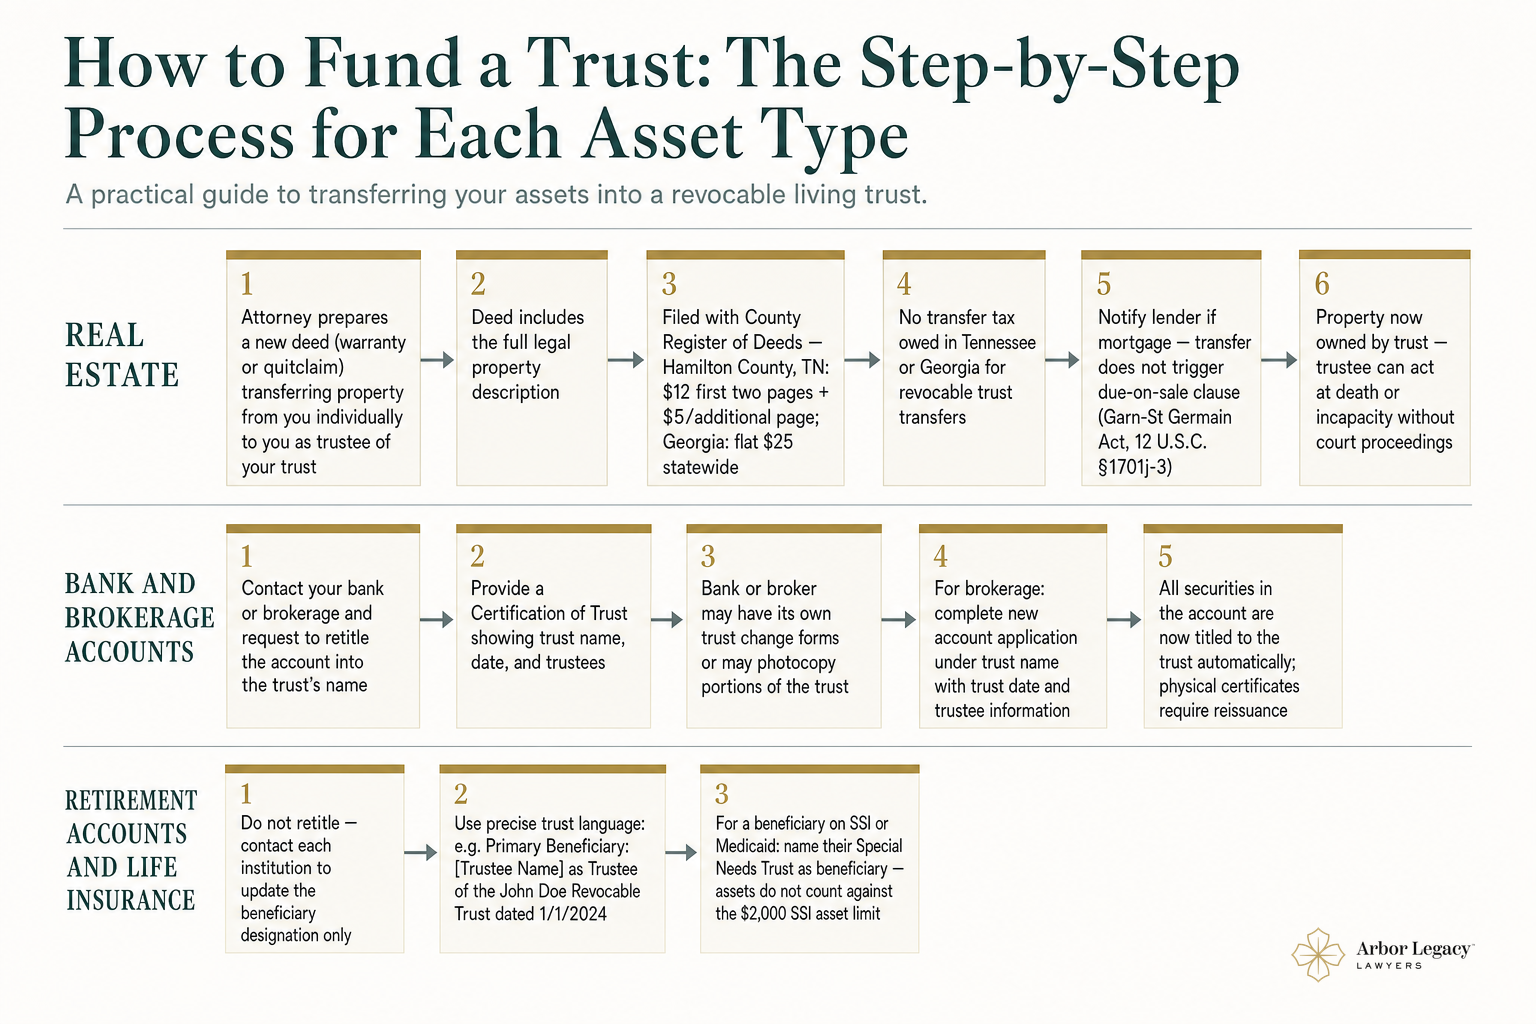
Transferring real property into a trust requires a new deed, typically a warranty deed or quitclaim deed, prepared by an attorney and recorded with the county. The deed names the trustee, usually you during your lifetime, as owner in trustee capacity. In Tennessee, transfers to or from a revocable living trust by the transferor or their spouse are exempt from state transfer tax under Tenn. Code Ann. § 67-4-409. Georgia's transfer tax is $1 per $1,000 of consideration and applies when property is conveyed for value, and specific categories of no-consideration transfers are exempt under Georgia Code § 48-6-2. Recording fees typically fall in the tens of dollars per deed.
The Financial Account Transfer Process
For bank and brokerage accounts, contact the institution and request a change of ownership to the trust. Most have standard forms and will ask for a certification of trust, which shares key details without revealing private terms. These legal documents are standard across most institutions, so call ahead to learn exactly what documentation your bank needs before you visit.
How a Funded Trust Protects Your Family Beyond Death
Protection During Your Lifetime Too
A funded revocable living trust does more than direct assets after death, it protects your family if you become incapacitated. When assets sit inside the trust, your successor trustee can step in immediately to manage them without court-supervised guardianship or conservatorship, which is especially important for long term care situations. An estimated 1.3 million U.S. adults are under court-appointed guardianship, with roughly $50 billion in assets under guardianship arrangements, according to the U.S. Senate Special Committee on Aging, often because no plan was in place. If someone has asked you to serve, our guide on what to know if you have been asked to serve as trustee explains the role.
Kids Protection Planning and the Trust Connection
For parents of minor children, a funded trust works alongside Kids Protection Planning so children are raised by the people the parents choose, with money available immediately for their care. Without funding, even a thoughtful trust cannot release funds for a child until probate resolves. Estate taxes rarely apply to young families, since fewer than 0.1 percent of estates owe federal estate tax, per the Tax Policy Center, and none of these states impose their own. The focus is immediate access, not tax.
Your Trust Needs to Stay Funded as Your Life Changes
New Assets Require New Funding
Every asset acquired after the trust is created, a new home, an inheritance, a new brokerage account, must be deliberately titled into the trust or it falls outside it. With about 5 million existing homes sold in 2022 per National Association of Realtors data reported by the Associated Press, many buyers with existing trusts simply forget to record a new deed. Any major purchase should trigger a funding review.
Regular Reviews Catch Gaps Before They Become Crises
A periodic review, ideally every three to five years or after major life events, should include a funding audit comparing what you own to what your trust holds. Just half of adults 50 and older currently have a legal will even though 93 percent say an updated document is important, according to AARP. There is a reason quick and simple estate plan reviews do not really exist. This ongoing guidance is the heart of a Life & Legacy Planning relationship and a natural part of the estate planning process.
Frequently Asked Questions About Funding a Trust
How much money is needed to fund a trust?
There is no minimum. You can transfer assets of any value into a trust regardless of net worth, according to New York Life.
What does it mean to fund my trust?
Funding means changing the legal ownership of your assets so they are held in the trust's name, and updating beneficiary designations to name the trust for life insurance and retirement accounts.
What happens if a trust is not funded?
Assets never transferred will likely go through probate court regardless of what the trust says. As one columnist put it, an unfunded living trust is essentially meaningless and wasteful, reported by MySanAntonio.
How do beneficiaries get money from a trust?
After the trust creator dies or becomes incapacitated, the successor trustee distributes assets according to the trust's instructions, in the optimum case without any court involvement, as Bradley Fogel explains in the Saint Louis University Law Journal. Simple trusts can begin distributions within a few months, while probate often takes over a year.
Can I fund my trust myself, or do I need an attorney?
Some steps, like updating a bank account, you can handle directly. Real estate transfers require a properly drafted deed prepared by an estate planning attorney and recorded with the county, since mistakes can create title problems, tax consequences, or gaps that defeat the trust's purpose.
What to Do Right Now If Your Trust May Not Be Fully Funded
A trust document without funded assets is a safety net full of holes, and an unfunded outcome is the default if nothing is done. Understanding how trust funds work is essential to making your plan effective. Arbor Legacy Lawyers helps families across Tennessee, Georgia, and North Carolina not just create estate plans but make sure those plans actually work, including a clear review of what is and is not inside your trust. Working with an estate planning attorney ensures your funding is completed correctly. Matthew "Web" W. Raulston focuses on the retitling and deed work that funding depends on. If you have a trust and are not certain your assets are properly titled inside it, a Life & Legacy Planning Session is the right next step. Get started with Arbor Legacy Lawyers and protect the people you love.
This article is a service of Arbor Legacy Lawyers P.C. and is provided for educational and informational purposes only. It does not constitute legal advice and does not create an attorney-client relationship. Estate planning laws vary by state; consult a qualified attorney about your specific situation.
Matthew "Web" W. Raulston
Father & Estate Planning Attorney, Arbor Legacy Lawyers P.C.
Arbor Legacy Lawyers, P.C.